
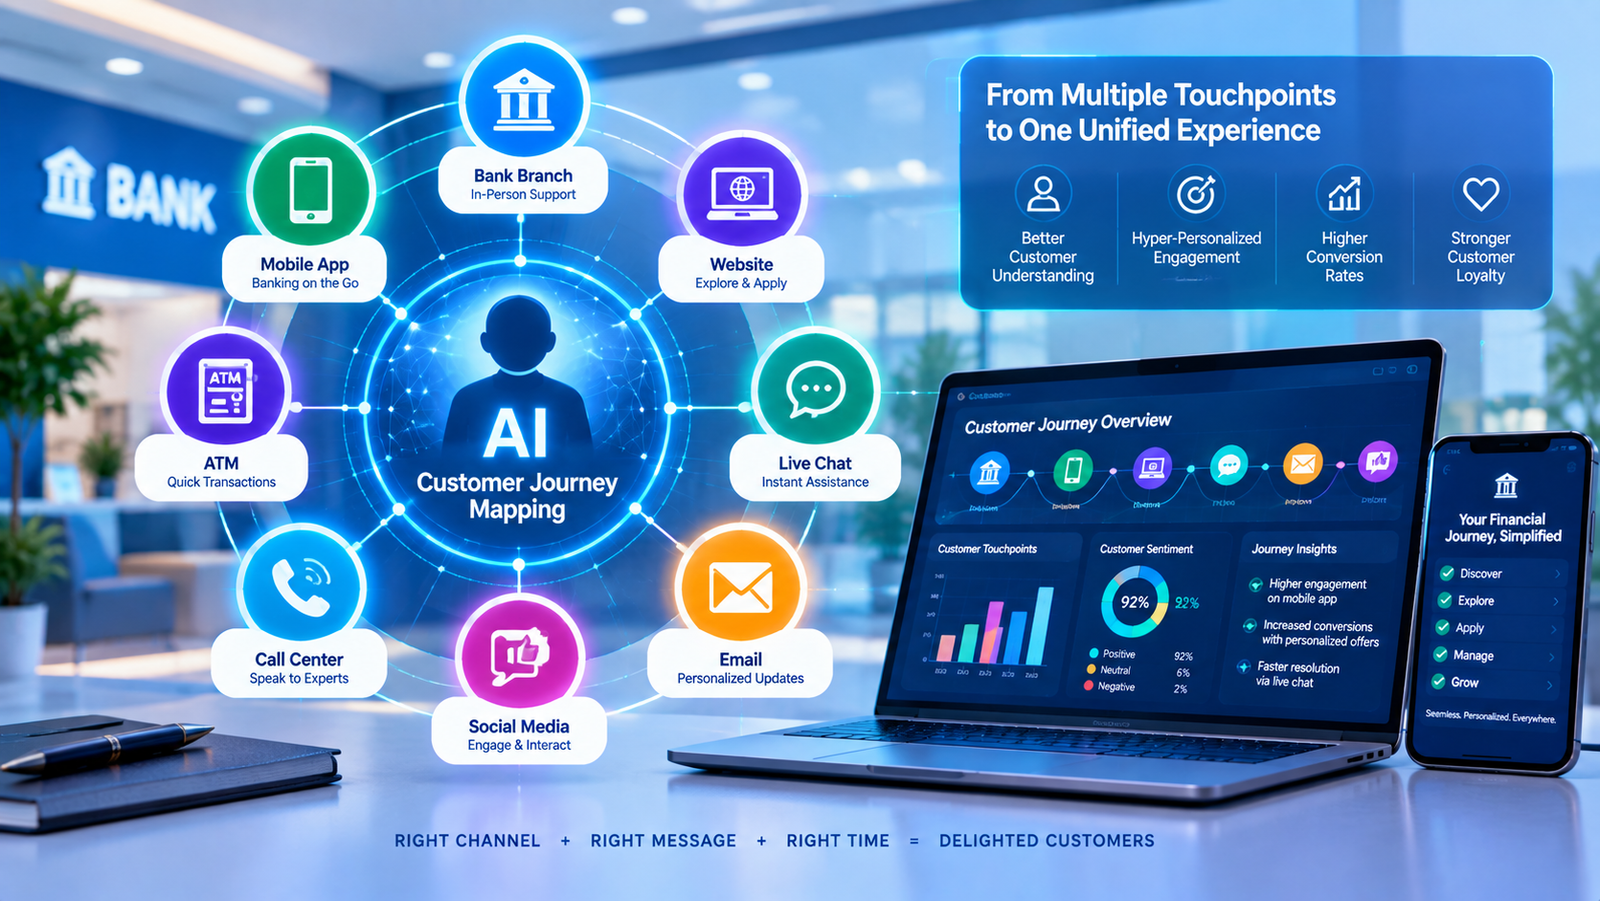
Primary topic: Artificial intelligence in banking customer journey analytics and omnichannel experience optimization
Research focus: Customer journey mapping, cross-channel data integration, predictive journey analytics, next-best-action models, customer experience personalization, journey orchestration, banking customer retention, conversational AI, customer friction detection and real-time decisioning
Understanding AI in Omnichannel Customer Journey Mapping
Omnichannel customer journey mapping is the process of understanding how customers interact with a bank across different channels while completing a task or meeting a financial need. A customer might discover a savings account through a search engine, compare its features on the bank’s website, begin an application on a mobile phone, contact customer support for clarification and complete the application later. If each channel operates independently, the bank may treat these interactions as separate activities instead of recognizing one connected journey.
AI helps connect these interactions and identify what customers are trying to accomplish. It can analyze behavioral events, transaction patterns, support conversations, application progress and service outcomes to build a more complete view of the customer experience.
The objective is not simply to personalize marketing messages. It is to make banking journeys easier to complete, more consistent across channels and more responsive to customer needs.
Mobile, web, branch and support channels operate as separate experiences. Customers may need to repeat information or restart a task when switching channels.
Channels share relevant context, allowing customers to continue a task, receive consistent information and access suitable support without unnecessary repetition.
Why Customer Journey Mapping Matters in Banking
Banking journeys often involve sensitive information, identity checks, financial decisions and multiple approval steps. A small point of friction can prevent a customer from completing an application or resolving a problem. A confusing verification screen, an unexplained decline, a failed payment or a support agent who cannot see previous interactions can turn a simple task into a frustrating experience.
The challenge is that banks often measure individual channel performance rather than the complete journey. A mobile app may receive strong engagement metrics while customers repeatedly abandon a loan application. A contact center may resolve calls quickly while customers need to contact the bank several times for the same issue.
AI-powered journey analytics can connect these signals and show where the customer experience breaks down.
Common banking journeys include:
- Opening a current, checking or savings account
- Completing digital identity verification and onboarding
- Applying for a credit card, personal loan or mortgage
- Making a payment or resolving a failed transaction
- Reporting a lost card or suspicious transaction
- Changing account details or managing financial preferences
- Moving from self-service to a human support agent
- Receiving financial guidance or exploring another banking product
Each journey has a different purpose, risk level and definition of success. A successful account opening requires more than a completed application form. The customer may still need to fund the account, activate a card, make a first transaction and understand how to use the service.
Research Study: AI-Powered Personalization in Digital Banking
A 2025 review published in the American Journal of Interdisciplinary Studies examined AI-powered personalization in digital banking. The researchers analyzed 111 peer-reviewed articles published between 2014 and 2024 using a PRISMA 2020-based review process.
The review organized the literature around seven themes, including AI techniques, behavioral data modeling, predictive analytics, customer engagement, ethical governance, emerging-market applications and research limitations. It identified machine learning, natural language processing, recommendation systems and sentiment analysis as important approaches for tailoring digital banking experiences.
For customer journey mapping, the key implication is that personalization depends on understanding customer behavior in context. A bank can use interaction history and behavioral signals to make a relevant service available at the right point in a journey. For example, a customer who repeatedly visits a card activation guide may need clearer instructions rather than another promotional message.
The review also highlighted privacy concerns, inconsistent measurement frameworks and limited longitudinal evidence. These limitations matter because a personalization system may increase clicks without improving customer outcomes. Banks should therefore evaluate whether AI makes a journey easier to complete, reduces unnecessary contact and improves customer understanding.
Research Study: Customer-Facing AI Adoption in Mobile Banking
A systematic review published in 2026 examined customer adoption, use and post-adoption behavior involving customer-facing AI in mobile banking. Following a PRISMA-based process, the researchers screened 448 records and included 22 studies.
The review found that trust, satisfaction and attitude were consistently associated with customer decisions and outcomes. However, the evidence was concentrated on intentions and evaluations rather than observed behavior. Of 17 studies with a separable focal response, 14 examined intention or evaluation, while only three measured use, choice or sustained use. None tracked actual abandonment.
This finding is directly relevant to AI-powered journey mapping. A bank may receive positive feedback about an AI assistant without knowing whether the assistant helps customers complete a task. Similarly, a customer may express an intention to use a personalized banking feature but never return to it.
Banks should connect experience research with behavioral data. Useful measures include completed applications, successful self-service resolution, repeat usage, reduced repeat contact and journey abandonment. Longitudinal measurement is particularly important when evaluating whether AI improves customer relationships over several months.
Research Study: Channel Cohesion and Customer Empowerment in Digital Banking
A 2026 study published in SAM Advanced Management Journal examined how channel integration affects customer experience in omnichannel banking. The researchers collected survey responses from 300 banking customers and used structural equation modeling to assess relationships among channel integration, customer empowerment, experience and relational outcomes.
The findings indicated that channel integration was associated with a better customer experience. Customer empowerment strengthened this relationship, while improved experience was associated with higher satisfaction, repurchase intentions and positive word-of-mouth.
This research adds an important dimension to journey mapping: a seamless experience is not only about moving data between systems. Customers also need control over how they interact with the bank.
For example, a customer should be able to choose whether to continue through the app, speak to an agent or visit a branch. The bank should preserve relevant context when the customer changes channels, but it should not use personalization to remove meaningful choices or pressure the customer into a product.
For AI systems, empowerment can be supported through clear explanations, adjustable communication preferences, transparent recommendations and easy access to human assistance.
Research Study: Omnichannel Banking and Continuance Intention
A 2026 study titled Seamless Banking: Investigating Customer Experience in the Omni-Channel Era examined how customer motivations relate to experience and the intention to continue using omnichannel banking.
The researchers surveyed 220 people with omnichannel banking experience in India and used structural equation modeling. Utilitarian motivation, which relates to practical usefulness and task completion, had a stronger and more robust relationship with customer experience and continuance intention than hedonic motivation. Hedonic motivation influenced customer experience but did not significantly affect continuance intention in the reported model.
For journey design, this suggests that convenience and practical value deserve close attention. Customers need to complete essential tasks reliably, understand what happens next and avoid repeating steps. A visually engaging app may improve the experience, but it cannot compensate for a failed transfer, an unclear application process or a support journey that repeatedly sends the customer between departments.
AI should therefore prioritize task success, relevant assistance and friction reduction before optimizing decorative or entertainment-oriented features.
The study was based on a survey of customers in one national context, so its results should not be assumed to apply identically to every banking market.
Source: Seamless Banking: Investigating Customer Experience in the Omni-Channel Era, 2026
Research Study: Omnichannel Banking and Brand Engagement Across Countries
A 2026 study in Management Decision examined omnichannel perception, customer experience and brand engagement across five countries: Argentina, Brazil, Spain, Mexico and the United States.
The research surveyed 2,029 bank users and used a cross-cultural quantitative approach. Its findings supported a positive relationship between omnichannel perception, customer experience and brand engagement. The multi-country design is useful because customer expectations and banking habits can differ across markets.
For banks operating internationally, a single journey design may not work equally well for every customer group. Customers may differ in their preferred channels, comfort with digital identity verification, expectations about human support and use of mobile banking.
AI can help identify these differences, but personalization should be grounded in legitimate, relevant signals rather than unsupported assumptions about a person’s identity or background. Banks should test journeys across customer segments and markets, then investigate performance gaps before deploying changes widely.
Source: Brand Engagement in Omnichannel Banking Services: A Cross-Cultural Approximation, 2026
Research Study: AI-Powered Personalization and Banking Customer Value
In September 2026, McKinsey published an analysis of AI-powered personalization in banking. The article describes how banks can use customer data, predictive models, real-time triggers and coordinated communication to improve customer engagement and value.
It identifies four connected capabilities: customer data and decision-making, personalized campaigns and journeys, measurement and marketing technology, and the operating model and talent needed to sustain the approach.
The article also describes the importance of integrating service interactions with personalized engagement. A bank can use transaction events or customer activity to identify when a message or service may be relevant, while continuous testing helps determine which interventions improve outcomes.
For journey mapping, the central lesson is that insight and action must be connected. A dashboard that identifies customer friction has limited value if the bank cannot change the relevant process, message or support workflow. Journey analytics should feed into a governed decision system that can trigger an appropriate response and measure what happened afterward.
What These Studies Mean for Banking Journey Design
The research points toward a practical conclusion: banks should not judge AI journey mapping only by how much data it collects or how sophisticated its models appear. It should be judged by whether it helps customers complete important tasks, receive consistent support and retain control over their financial decisions.
| Research insight | Implication for AI journey mapping | What to measure |
|---|---|---|
| Personalization research spans multiple AI methods | Use behavioral context to provide relevant help | Task completion and usefulness |
| Actual post-adoption behavior is under-studied | Track real behavior over time, not only stated intent | Repeat usage and abandonment |
| Channel integration improves experience | Preserve task context across channels | Repeat explanations and handoff success |
| Customer empowerment strengthens experience | Keep choices, transparency and human support available | Resolution, satisfaction and opt-out rates |
| Practical usefulness matters for continuance | Prioritize reliable task completion over superficial engagement | Successful completion and repeat contact |
How AI Maps the Complete Banking Customer Journey
An AI-powered journey platform combines events from different channels and organizes them around a customer goal. The system must distinguish between a channel interaction and the broader task that the customer is trying to complete.
Consider a customer applying for a credit card. The customer may read a product page, use a repayment calculator, begin an application, pause during identity verification, contact support and return to finish the application. A channel-level dashboard may count these as separate events. A journey model connects them into one sequence and identifies the point where progress stopped.
App, web, branch and support events
Identity, consent and task context
Friction, intent and next steps
Relevant support or intervention
Completion and customer outcome
Core AI Technologies for Omnichannel Journey Mapping
Machine Learning for Journey Segmentation
Machine learning can group customers according to observed needs, behavior and journey patterns. Instead of relying only on broad demographic segments, a bank can identify customers who are actively completing a task, repeatedly seeking support or showing signs of difficulty.
These segments should be based on relevant and permitted data. A segment is useful when it helps the bank improve a service or provide appropriate assistance, not simply when it enables more aggressive targeting.
Predictive Analytics for Journey Abandonment
Predictive models can estimate whether a customer is likely to stop before completing a process. Signals may include repeated errors, long pauses, multiple failed verification attempts, repeated visits to help pages or a sudden change in the normal journey sequence.
The model can trigger a suitable intervention, such as clearer instructions, a save-and-resume option or an offer to speak with support. It should not automatically make a credit, eligibility or account decision unless the model has been specifically designed, validated and governed for that purpose.
Natural Language Processing for Customer Feedback
Natural language processing can analyze support conversations, complaints, survey responses and other permitted text to identify recurring customer concerns. It can group complaints by topic, detect changes in language and connect feedback to particular journey stages.
For example, a sudden increase in complaints mentioning a confusing fee disclosure may indicate a problem in a product application journey. Linking text analytics with behavioral data helps the bank identify both what customers say and where the issue occurs.
Generative AI for Journey Summaries and Agent Assistance
Generative AI can summarize a customer’s previous interactions for an authorized support agent, explain the current status of a service request or help staff locate relevant procedures. It can reduce the need for customers to repeat their situation when moving from a chatbot to a human agent.
However, summaries must be grounded in reliable records. The system should distinguish verified account facts from generated interpretations, avoid exposing information to unauthorized staff and allow agents to inspect the underlying interaction history.
Recommendation Models for Next-Best Action
A next-best-action model selects a suitable action based on the customer’s current task and the bank’s service rules. In a journey context, the best action may be to provide help, explain a fee, remind the customer of an unfinished task or do nothing.
This is an important distinction. A system designed only to maximize product conversion may recommend offers at moments when customers need service support. A responsible model should consider customer intent, relevance, suitability, contact frequency and the risk of causing confusion.
Visual: Where AI Can Improve the Banking Journey
AI capability: Intent classification and topic analysis
AI capability: Abandonment prediction and friction detection
AI capability: Anomaly detection and contextual recommendations
AI capability: Conversation summarization and case routing
AI capability: Behavioral forecasting and journey optimization
Building a Unified Customer Journey Data Layer
AI cannot reliably map journeys if the underlying data is incomplete, inconsistent or disconnected. Banks often operate separate systems for mobile banking, customer relationship management, card processing, loan origination, fraud monitoring and contact-center operations.
A unified journey layer does not necessarily require replacing every legacy system. It requires a reliable way to connect relevant events, preserve timestamps and define consistent meanings for customer actions.
| Data source | Useful journey signals | Potential application |
|---|---|---|
| Mobile and web analytics | Page views, errors, task steps and exits | Detect digital friction |
| CRM and customer service | Cases, complaints, contact reasons and outcomes | Improve service continuity |
| Application systems | Started, pending, approved and abandoned stages | Improve application completion |
| Transaction systems | Payment outcomes and relevant account events | Provide timely service assistance |
| Branch and ATM systems | Appointments, service events and assisted tasks | Connect physical and digital journeys |
| Feedback and surveys | Satisfaction, complaints and reported difficulties | Identify experience problems |
Customer identity resolution must be handled carefully. A bank needs to connect events to the correct customer or session, but it should not combine identities merely because some attributes look similar. Incorrect identity matching can expose private information and produce misleading journey analysis.
Real-Time Journey Orchestration
Journey mapping becomes more valuable when the bank can act on the insights. Real-time orchestration uses customer events and decision rules to select an appropriate response across available channels.
For example, if a customer encounters repeated errors during a card payment, the bank might display a clear explanation, provide a safe troubleshooting path or make it easier to contact support. If a customer has already resolved the issue through a call center, the system should suppress an irrelevant automated message.
Show a clear explanation and expected next step
Offer secure support or case creation
Apply the bank’s approved security process
The AI system should not bypass fraud controls or change transaction permissions simply to improve the customer experience. Security decisions must remain governed by the bank’s approved controls.
Measuring Customer Journey Performance
Banks need a measurement framework that connects customer experience with operational and business outcomes. Engagement metrics can help explain behavior, but they should not be treated as proof that a journey has improved.
Useful metrics include:
- Journey completion rate: The share of customers who successfully complete the intended task
- Stage-level abandonment: The proportion of journeys that stop at each step
- Time to completion: The time required to complete a task, with complex cases analyzed separately
- First-contact resolution: The share of service issues resolved during the first interaction
- Repeat-contact rate: How often customers contact the bank again about the same issue
- Channel handoff success: Whether customers can continue a task after changing channels
- Customer satisfaction: Feedback collected after a relevant interaction
- Complaint recurrence: Whether the same problem continues to generate complaints
- Incremental conversion: The additional completed outcomes attributable to an intervention
- Customer retention: Whether improvements are associated with sustained customer relationships
Where possible, banks should use controlled experiments or credible comparison groups to distinguish the effect of AI from seasonal changes, product changes or other campaigns. A rise in conversion after deploying a model does not automatically prove that the model caused the improvement.
Privacy, Security and Responsible Personalization
Banking journey data can reveal sensitive information about a customer’s finances, behavior and personal circumstances. Combining data across channels increases the potential value of analytics, but it also increases the consequences of misuse or unauthorized access.
Responsible journey mapping should follow data minimization and purpose limitation. Banks should collect only the data needed for a defined use case, apply appropriate consent and access controls, and retain information only as permitted by applicable law and policy.
AI models also require fairness and performance testing. A journey prediction model may perform differently across customer groups because of missing data, inconsistent digital access or historical differences in service quality. If the model directs some customers toward less effective support, it can reinforce existing barriers.
Recommended safeguards:
- Use only authorized data for the stated purpose
- Apply role-based access controls and encryption
- Keep audit logs for important automated decisions
- Test model performance across relevant customer groups
- Provide clear explanations for important recommendations
- Allow customers to manage communication and personalization preferences
- Maintain a clear route to human support
- Monitor model drift and investigate unexpected outcomes
- Separate service assistance from credit or eligibility decisions
For US banks, relevant requirements may include applicable GLBA privacy and safeguards obligations, fair lending rules where credit is involved, and relevant federal and state consumer-protection requirements. Banks operating in other markets must map their controls to local privacy, banking and consumer-protection laws.
Expert Recommendation
Banks should begin with a small number of high-value journeys rather than attempting to create a universal customer data platform before delivering any improvement. Account opening, card activation, payment problem resolution and loan application completion are useful candidates because each has a clear starting point, a measurable outcome and identifiable friction points.
The recommended approach is to establish the baseline journey, connect the minimum required data, identify the most costly or frequent failure points, and introduce AI only where it can improve a specific decision. A model that predicts abandonment is useful only if the bank has an appropriate intervention, such as clearer instructions or a better handoff to support.
The bank should then test the intervention against a suitable comparison group. If it improves completion without increasing complaints, privacy risk, unfair outcomes or unwanted contact, it can be expanded to additional journeys.
Expert Quote
“The banking industry’s next growth curve won’t be won by scale but by precision.”
Source: McKinsey, Global Banking Annual Review 2025
In the context of customer journeys, precision means understanding what the customer is trying to do and responding appropriately. It does not mean sending more messages or making every interaction feel personalized. A precise intervention can be as simple as explaining a failed payment, preserving an unfinished application or routing a complex issue to the right person.
Implementation Roadmap
Weeks 1–3
Define the customer task, business objective, baseline metrics, relevant systems and ownership.
Weeks 3–7
Normalize events, resolve identities where authorized, check data quality and document consent and access rules.
Weeks 7–11
Identify journey drop-offs, train a focused model and validate its performance against a baseline.
Weeks 11–15
Run a controlled pilot, monitor customer outcomes and review complaints, fairness and operational impact.
Ongoing
Scale successful interventions, monitor model drift and extend the approach to other customer journeys.
Future Predictions: 2027–2030
2027: Journey Analytics Moves Closer to Real-Time Decisions
Banks are likely to connect journey analytics more closely with event-driven systems. Rather than reviewing abandonment reports only after a campaign or quarter ends, teams will increasingly detect problems while customers are still completing a task. Real-time support prompts, contextual explanations and secure handoffs will become more practical where data quality and system integration allow them.
2028: AI Agents Support More Complex Service Journeys
Generative AI assistants are likely to handle more multi-step service tasks, such as explaining application status, gathering information for a support case or guiding customers through routine account-management processes. Banks will need stronger permission controls, transaction limits, confirmation steps and escalation rules as these assistants gain the ability to take actions rather than only provide answers.
2029: Journey Models Become More Outcome-Oriented
Banks will increasingly evaluate AI using complete journey outcomes rather than isolated engagement metrics. Models may optimize for successful resolution, reduced repeat contact, customer effort and sustained product use. More longitudinal evidence should also help banks understand whether personalization improves customer relationships or simply shifts activity between channels.
2030: Continuous Journey Optimization Becomes a Banking Capability
A more mature architecture may connect journey analytics, customer service, product systems and governed AI decisioning in a continuous improvement loop. Systems could identify a recurring friction point, recommend a process change, test the intervention and report its effects. Human teams will remain important for policy decisions, complex cases, customer complaints and oversight of automated actions.
These are reasoned projections based on current research and industry direction, not guaranteed outcomes. Their pace will depend on regulation, legacy-system integration, data quality, customer trust and the reliability of AI systems.
Business Opportunities for Fintech and AI Development Companies
Banks may build journey capabilities internally, buy specialist platforms or combine both approaches. This creates opportunities for AI and software companies that can solve specific integration and measurement problems.
- Customer Journey Intelligence Platform: Connect channel events and reveal where customers encounter friction
- AI Journey Analytics API: Provide journey-stage classification and behavioral insights to existing banking systems
- Application Abandonment Prediction: Identify customers who may need help completing onboarding or a product application
- Contact Center Journey Copilot: Summarize previous interactions and provide relevant case context to authorized agents
- Real-Time Journey Orchestration: Select appropriate service interventions based on current customer activity
- Customer Feedback Intelligence: Connect complaint themes and sentiment with specific journey stages
- Omnichannel Measurement Layer: Standardize completion, handoff, resolution and repeat-contact metrics
- Privacy-Aware Personalization: Support customer-specific experiences with consent, purpose limitation and auditability
The clearest product opportunity is not another generic chatbot. It is a platform that connects a specific banking journey to a measurable improvement and integrates with the bank’s existing systems without requiring a complete technology replacement.
Frequently Asked Questions
What is AI in omnichannel customer journey mapping?
AI in omnichannel customer journey mapping uses machine learning, behavioral analytics, natural language processing and other AI techniques to understand how customers move across banking channels. It helps banks identify friction, predict customer needs and provide more consistent support throughout a task.
How does AI improve the banking customer experience?
AI can identify repeated errors, predict where customers may abandon a process, summarize previous support interactions and provide relevant guidance. Its impact should be measured through completed tasks, successful resolutions, customer feedback and other meaningful outcomes rather than engagement alone.
What data is needed for AI-powered journey mapping?
Depending on the use case, banks may use mobile and web events, application status, customer-service records, transaction outcomes, branch interactions and feedback. Data should be collected and connected only where permitted and necessary for the defined purpose.
Can AI predict customer journey abandonment?
Yes. Models can use signals such as repeated errors, incomplete steps, long pauses and previous journey patterns to estimate the likelihood of abandonment. Predictions should be validated on current data, and any intervention should be tested to confirm that it actually improves completion.
How is omnichannel banking different from multichannel banking?
Multichannel banking offers several ways to access services, but those channels may operate separately. Omnichannel banking connects relevant information and processes so customers can continue a task across channels with less repetition and more consistent support.
Does AI journey mapping require replacing legacy banking systems?
Not necessarily. Banks can begin by integrating selected events and data from existing systems through APIs, event pipelines or other approved interfaces. A focused use case can demonstrate value before the bank expands the data architecture.
What are the main risks of AI customer journey analytics?
Key risks include privacy violations, incorrect identity matching, biased predictions, poor-quality data, excessive personalization, opaque recommendations and automation errors. Banks should apply access controls, validation, audit trails, human escalation and ongoing monitoring.
How should banks measure the success of AI journey mapping?
Banks should measure journey completion, stage-level abandonment, time to completion, first-contact resolution, repeat-contact rate, handoff success, customer satisfaction and sustained retention. Controlled experiments can help determine whether an AI intervention caused an improvement.
Final Perspective
AI in omnichannel customer journey mapping is most valuable when it helps a bank understand the customer’s goal, identify what is preventing progress and improve the next interaction. It connects the customer experience across mobile apps, websites, branches, ATMs and support channels, allowing banks to move beyond isolated channel metrics.
The research also shows why implementation must be specific and evidence-led. Studies of digital banking personalization identify opportunities for more relevant experiences, while recent research on customer-facing AI highlights the lack of longitudinal evidence about actual use and abandonment. Research on channel integration and customer empowerment further indicates that continuity works best when customers retain control and can choose how to interact with the bank.
For banks, the practical priority is to select a high-value journey, connect the minimum necessary data, identify measurable friction and deploy a focused AI intervention. The system should preserve security and privacy, provide a route to human support and measure whether the customer’s problem was genuinely resolved.
The long-term opportunity is a banking experience that learns from customer journeys without making customers feel tracked, pressured or trapped in automation. AI should help banks become more useful, more consistent and easier to deal with.
Research Sources
- AI-Powered Personalization in Digital Banking: A Review of Customer Behavior Analytics and Engagement, 2025
- Consumer Adoption, Use, and Post-Adoption of Customer-Facing AI in Mobile Banking: A Systematic Review, 2026
- From Fragmentation to Integration: How Channel Cohesion and Empowerment Improve the Customer Journey in Digital Banking, 2026
- Seamless Banking: Investigating Customer Experience in the Omni-Channel Era, 2026
- Brand Engagement in Omnichannel Banking Services: A Cross-Cultural Approximation, 2026
- McKinsey, At Last, Customers First: AI-Powered Personalization Can Help Banks Create Value, September 2026
- McKinsey, Global Banking Annual Review 2025
- Gartner, Top Digital Customer Experience Trends for Bank CIOs in 2026
- Gartner, Hype Cycle for Banking Customer Experience, 2025

Leave a Reply