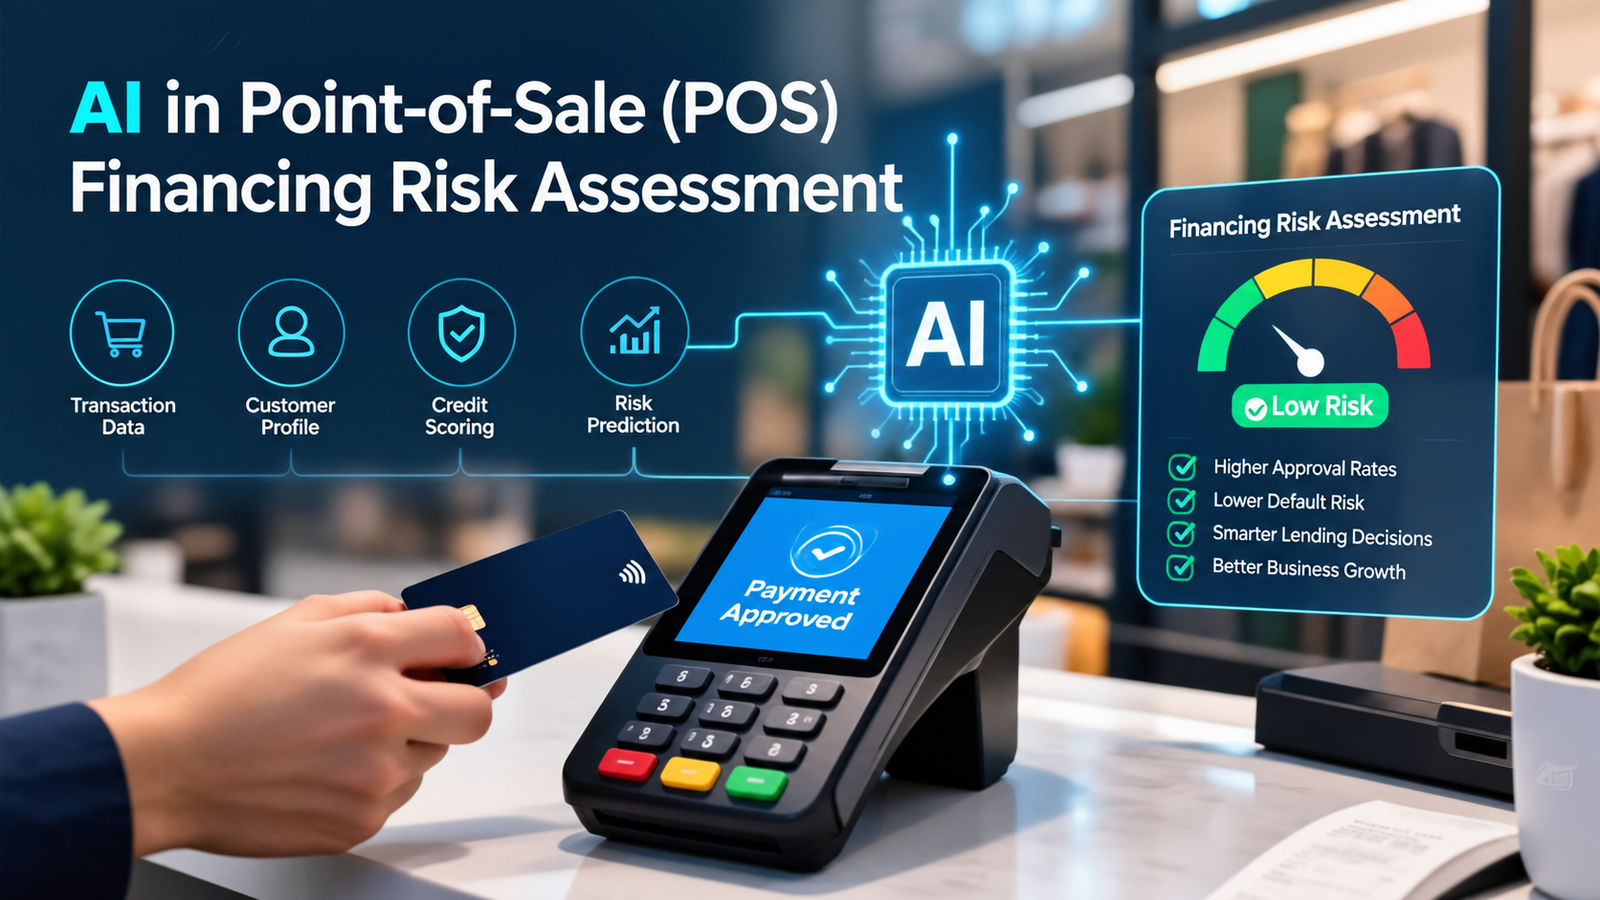
Primary topic: AI in Point-of-Sale (POS) Financing Risk Assessment
Research focus: AI-powered POS lending, Buy Now Pay Later (BNPL), real-time credit scoring, alternative data, default prediction, affordability assessment, fraud detection, explainable AI, responsible lending, model risk, and the future of intelligent embedded finance.
What Is Point-of-Sale Financing Risk Assessment?
Point-of-sale financing allows a consumer to obtain credit while purchasing a product or service. The financing decision is embedded directly into the checkout process instead of requiring the customer to complete a separate traditional loan application.
Buy Now Pay Later is one common form of POS financing. In the United States, BNPL products commonly allow consumers to split a retail purchase into four or fewer payments, although POS financing also includes longer-term installment products and other embedded credit arrangements. The CFPB notes that BNPL can be offered online as well as in physical stores.
Source: Consumer Financial Protection Bureau
Risk assessment is the process used by the lender to determine whether a proposed transaction represents an acceptable level of credit risk.
A POS risk engine may need to answer several questions almost instantly:
- Is the applicant likely to repay?
- Can the applicant reasonably afford the proposed payments?
- Is the application potentially fraudulent?
- Does the transaction look consistent with the customer’s normal behavior?
- Is the requested financing amount appropriate?
- Does the customer have excessive existing obligations?
- Should the lender approve, decline, or offer different terms?
- Is additional verification required?
Traditional credit scoring can answer some of these questions, but POS financing creates a different operating environment.
The lender may have only seconds to make the decision. The requested loan may be relatively small. The customer may have a limited traditional credit history. The merchant may want a low-friction checkout experience. At the same time, the lender must control fraud, credit losses, regulatory risk, and customer harm.
This is where AI becomes particularly relevant.
Why AI Is Important for POS Financing
Traditional credit models often depend heavily on established credit history and structured application information.
POS financing can produce a much richer decision environment.
The system may be able to analyze:
Credit history, utilization and repayment behavior
Purchase amount, frequency and basket characteristics
Application and repayment behavior
Identity, device and transaction anomalies
Additional financial or contextual information where legally permitted
Machine learning can identify nonlinear relationships among these variables.
Instead of simply asking whether a borrower has previously missed a payment, an AI system can estimate how different combinations of factors affect the probability of delinquency.
For example, the model may identify a combination of:
- High recent credit utilization
- Multiple simultaneous financing applications
- Rapid increases in purchase frequency
- Large transaction amounts relative to historical behavior
- Recent payment deterioration
The individual variables may not be decisive on their own. Their combination can provide a more informative risk signal.
POS Financing vs Traditional Credit Underwriting
| Factor | Traditional lending | AI-enabled POS financing |
|---|---|---|
| Decision time | Minutes to days depending on product | Potentially seconds |
| Primary data | Application and credit history | Credit, transaction, behavioral and other permitted data |
| Customer experience | Separate application process | Embedded within checkout |
| Risk response | Periodic model updates | Can support real-time monitoring |
| Fraud integration | Often separate or downstream | Can be integrated directly into the decision engine |
| Explainability | Usually easier with conventional scorecards | Requires explicit explainability and governance design |
The main advantage is speed and richer decisioning.
The main challenge is that more data and more complex models do not automatically create better lending decisions.
Research Study 1: 2026 Systematic Review of AI-Based Credit Assessment
A 2026 systematic literature review published in Expert Systems with Applications examined 118 peer-reviewed studies published between 2018 and 2025 on AI-based credit assessment in digital lending.
The review specifically considered machine learning and hybrid models, alternative and behavioral data, real-time learning, explainability, and fairness-oriented governance.
The researchers identified substantial methodological progress, particularly in ensemble and hybrid approaches. At the same time, the literature remains more mature around predictive accuracy than around real-time adaptation, fairness, transparency, and governance.
This finding is directly relevant to POS financing.
A POS lender may be able to build a model that predicts default accurately in a historical dataset. That does not automatically mean the model is ready to make live checkout decisions.
A production system must also answer:
- How quickly does the model respond to changing customer behavior?
- Does performance remain stable across different merchant categories?
- Does the model behave consistently across customer groups?
- Can the lender explain a decline?
- Can the lender monitor model drift?
- Can the model distinguish credit risk from fraud risk?
The study therefore supports a broader view of AI credit assessment. Accuracy is important, but operational readiness requires transparency, adaptability, fairness, and governance.
Research Study 2: Machine Learning and Consumer Credit Risk
A foundational study published in the Journal of Banking & Finance evaluated machine-learning techniques for consumer credit risk using transaction and credit-bureau data from customers of a major commercial bank.
The researchers found that nonlinear machine-learning models could improve out-of-sample prediction of credit-card delinquencies and defaults. Under their assumptions, the estimated potential cost savings from decisions based on the forecasts ranged from 6% to 25% of total losses.
The study is older than the current wave of generative AI and BNPL, but its underlying lesson remains important.
Transaction behavior contains information that traditional credit variables may not capture completely.
This is highly relevant to POS financing because the transaction itself can become part of the risk signal.
For example, a lender could potentially evaluate whether:
- The purchase amount is unusual for the borrower
- The customer is making repeated financing applications
- Payment behavior is deteriorating
- The customer’s transaction patterns have changed sharply
The research does not prove that the same results will occur in today’s BNPL market. Its importance is that it demonstrates why transaction-level information can add predictive value to consumer credit models.
Source: Journal of Banking & Finance, Consumer credit-risk models via machine-learning algorithms
Research Study 3: AI and BNPL Credit Risk
A 2025 research article on BNPL examined how AI can help providers offer credit while managing the tensions between convenience, risk, consumer protection, and responsible lending.
The authors describe how BNPL providers use AI in areas including credit decisions and risk management.
The research is important because BNPL differs from conventional credit products.
A customer can potentially obtain several small loans from different providers without those obligations appearing immediately in a traditional credit profile.
This creates a major risk-assessment problem.
An individual transaction may look affordable when evaluated independently, while the customer’s total outstanding BNPL exposure may be much higher.
The research therefore points toward a key requirement for POS financing platforms:
Risk assessment should evaluate the customer at both the transaction level and the portfolio level.
Source: Buy Now, Pay Later: AI, Inherent Tensions, and Implications
Research Study 4: CFPB Research on BNPL Borrowers and Loan Stacking
The U.S. Consumer Financial Protection Bureau analyzed matched BNPL application and credit-record data from six major BNPL firms: Affirm, Afterpay, Klarna, PayPal, Sezzle, and Zip.
The CFPB reported that more than one-fifth of consumers with a credit record used BNPL in 2022.
More than three-fifths of BNPL borrowers held multiple simultaneous BNPL loans at some point during the year, and approximately one-third had loans from multiple BNPL providers.
The CFPB also found that BNPL users were more likely than other consumers to have higher balances on other unsecured credit lines.
Source: Consumer Financial Protection Bureau
This research reveals one of the biggest challenges for AI-powered POS financing.
Approval risk cannot be evaluated only at checkout.
Suppose a customer purchases a $500 product and qualifies for a four-payment financing plan.
The individual payment may appear manageable.
But the customer may already have:
- Three other BNPL loans.
- High credit-card utilization.
- A recent increase in borrowing.
- Other unsecured obligations.
An intelligent risk engine therefore needs to consider aggregate exposure where legally and operationally possible.
This creates an important architecture:
New POS Application
↓
Transaction Risk
↓
Customer Credit Risk
↓
Existing Debt / Exposure
↓
Affordability Assessment
↓
Fraud Assessment
↓
Final Credit Decision
Source: CFPB, Consumer Use of Buy Now, Pay Later and Other Unsecured Debt
Research Study 5: Explainable AI for E-Commerce Credit Risk
A 2025 study in Knowledge-Based Systems examined explainable deep-credit modeling in e-commerce lending.
The researchers focused on the challenge of using shopping and credit information while maintaining interpretability.
The study is particularly relevant to POS financing because e-commerce generates transaction information that can potentially help assess creditworthiness.
However, the key challenge is not merely prediction.
A lender needs to understand why the system produced a particular decision.
For example:
Weak explanation: “The AI score was below the threshold.”
Useful explanation: “The application was declined because of the model’s principal risk factors, including recent delinquency and high revolving-credit utilization.”
The second type of explanation is much more useful for both governance and customer communication.
Explainability also becomes important when a lender needs to investigate whether the model is using inappropriate or unstable signals.
Research Study 6: Machine Learning for Early Loan Default Prediction
A 2025 study published in Computational Economics examined machine-learning approaches for early loan-default prediction and explainability.
Early prediction is particularly valuable for POS financing because lenders can potentially identify deteriorating repayment behavior before an account becomes seriously delinquent.
The goal is not simply to approve or decline customers.
AI can also support post-origination risk management.
For example:
- Identify accounts showing increasing repayment risk.
- Prioritize accounts for customer support.
- Detect changes in payment behavior.
- Estimate expected losses.
- Support collections prioritization.
This creates a lifecycle model rather than a one-time underwriting model.
→
Approval
→
Purchase
→
Repayment Monitoring
→
Early Risk Detection
→
Intervention
→
Resolution
Source: Computational Economics, Machine Learning XAI for Early Loan Default Prediction
Research Evidence Dashboard
118 studies
Covered by a 2026 systematic review of AI-based digital lending credit assessment.
6 major BNPL providers
Included in CFPB matched application and credit-record research.
60%+
Of BNPL users in the CFPB study held simultaneous BNPL loans at some point.
6%–25%
Estimated potential loss reduction in an earlier ML consumer-credit study under its assumptions.
Real-time decisions
POS financing requires risk assessment within the checkout experience.
Explainability
AI credit decisions need understandable and defensible reasoning.
AI-Powered POS Risk Assessment Workflow
Customer Starts Checkout
↓
Identity & Application Data
↓
Credit & Permitted Alternative Data
↓
Transaction Analysis
↓
Fraud & Identity Risk
↓
AI Credit Risk Model
↓
Affordability / Exposure Check
↓
Explainability & Policy Rules
↓
Approve / Decline / Review / Alternative Terms
↓
Post-Origination Monitoring
The architecture should separate the AI prediction from the final policy decision.
For example, the AI model might generate a probability of default.
A policy engine can then determine how that probability maps to an approved financing amount.
This separation makes the system easier to audit and modify.
AI Credit Scoring for POS Financing
Machine learning models can be used to estimate several important risk outcomes.
| Model output | Purpose |
|---|---|
| Probability of default | Estimate likelihood of repayment failure |
| Probability of delinquency | Identify expected late-payment behavior |
| Fraud probability | Identify suspicious applications or transactions |
| Affordability score | Estimate whether proposed payments are manageable |
| Exposure risk | Estimate risk from total outstanding obligations |
| Expected loss | Support portfolio-level risk management |
A production system can combine these outputs rather than using one score for everything.
Alternative Data in POS Financing
One of the biggest opportunities for AI is the use of additional data.
Traditional lending often focuses on credit reports, income, employment, and application information.
Digital lending can potentially incorporate additional signals.
Examples may include:
- Transaction patterns
- Repayment behavior
- Account activity where legally permitted
- Purchase frequency
- Basket size
- Merchant category
- Application behavior
- Device and identity signals for fraud purposes
However, alternative data should not automatically be treated as beneficial.
The CFPB has previously noted that alternative data and machine learning can potentially improve credit decisions while also creating risks involving discrimination, transparency, privacy, and inaccurate predictions.
The critical question is therefore:
Does the data provide legitimate information about repayment risk without introducing unacceptable legal, fairness, privacy, or consumer-protection risks?
AI for POS Fraud Detection
Credit risk and fraud risk are related but different.
A borrower may have strong credit and still be involved in a fraudulent transaction.
A legitimate customer may also look unusual because of travel, a new device, a large purchase, or a temporary change in behavior.
A modern POS financing platform should therefore have separate but connected models.
Credit model
“Will this customer repay?”
Fraud model
“Is this transaction or identity suspicious?”
Affordability model
“Is this financing amount appropriate?”
Combining the three can produce a much stronger decision framework than using a single generic credit score.
AI for Merchant-Specific Risk
POS financing risk is also influenced by the product being financed.
A $200 grocery purchase and a $5,000 electronics purchase do not necessarily have the same risk characteristics.
The lender can potentially analyze:
- Average transaction value
- Return and refund behavior
- Merchant category
- Historical fraud rates
- Customer financing frequency
- Chargeback patterns
- Product resale characteristics
This creates an opportunity for contextual underwriting.
The AI model can evaluate both:
Who is borrowing?
and
What is being financed?
That does not mean product type should automatically determine creditworthiness. Rather, it can become one input into a broader risk framework where its use is legally permissible and validated.
Real-Time Affordability Assessment
One of the most important developments in POS financing will be the movement from creditworthiness toward affordability.
A customer may have a reasonable credit history but still face difficulty with a new payment obligation.
AI can potentially combine available financial information to estimate whether the requested payment fits within the customer’s current financial situation.
A simplified conceptual model could be:
Affordability assessment
Income indicators + existing obligations + recent repayment behavior + proposed payment + financial stress signals
↓
Estimated payment capacity
The actual variables and methodology must depend on the lender, product, jurisdiction, data permissions, and applicable law.
Explainable AI Is Not Optional for Credit Decisions
AI credit scoring becomes difficult when a lender cannot explain why an application was declined.
This is not simply a product-design issue.
In the United States, the CFPB has stated that creditors using complex algorithms, including AI and machine learning, must still comply with the Equal Credit Opportunity Act’s requirements for specific reasons when adverse action is taken. The CFPB states that technological complexity does not excuse noncompliance.
The CFPB’s 2025 supervisory material also reported findings involving AI/ML credit models with, in some cases, more than a thousand variables and noted problems with accurately identifying and validating the reasons used in adverse-action notices.
Source: CFPB Supervisory Highlights, Advanced Technologies
Expert Quotation
This statement from the CFPB captures one of the central challenges of AI-powered credit underwriting: model complexity does not remove the responsibility to produce legally compliant credit decisions and explanations.
Source: Consumer Financial Protection Bureau
Model Risk Management for POS Financing
The model itself becomes a risk that must be managed.
The OCC, Federal Reserve, and FDIC issued revised interagency model-risk guidance in April 2026. The guidance emphasizes model development and use, testing, validation and monitoring, governance and controls, and third-party model considerations. It also notes that generative AI and agentic AI models are novel and rapidly evolving and are not within the scope of that particular guidance.
For POS lenders, model governance should cover:
- Data quality
- Feature selection
- Model development
- Validation
- Performance monitoring
- Fairness testing
- Explainability
- Model drift
- Vendor models
- Version control
- Documentation
- Change management
A model should never become a black box that nobody in the organization fully owns.
Responsive AI POS Risk Architecture
1. Customer & application layer
Customer identity, application information and consent
2. Data layer
Credit data + permitted alternative data + transaction data
3. Fraud intelligence
Identity, device, transaction and behavioral anomaly detection
4. AI risk layer
Default probability + delinquency + affordability + exposure
5. Explainability layer
Principal factors and adverse-action reasoning
6. Policy engine
Credit policy + risk limits + product rules
7. Decision layer
Approve + decline + review + alternative offer
8. Monitoring layer
Repayment behavior + model drift + portfolio risk
9. Governance layer
Validation + audit + compliance + human oversight
POS Financing AI Risk Matrix
| Risk | Example | AI / technical control | Governance control |
|---|---|---|---|
| Default risk | Customer fails to repay | PD and delinquency models | Credit policy limits |
| Loan stacking | Multiple simultaneous BNPL obligations | Exposure aggregation | Affordability controls |
| Fraud | Stolen identity or account | Anomaly detection | Identity verification |
| Model bias | Unequal outcomes | Fairness monitoring | Compliance review |
| Explainability | Unclear decline reason | Explainable models and reason codes | Adverse-action controls |
| Model drift | Risk patterns change | Drift monitoring | Periodic validation |
| Data privacy | Excessive data collection | Data minimization and access control | Privacy governance |
AI for Post-Approval Risk Management
POS financing risk assessment should not end when the customer receives approval.
The lender can continue monitoring repayment behavior.
AI can identify early warning signals such as:
- Repeated late payments
- Increasing outstanding balances
- Sudden changes in repayment behavior
- Repeated financing requests
- Increasing utilization of available credit
The objective should not simply be to send more collection messages.
AI can also support earlier and more appropriate interventions.
For example, a lender could identify accounts that may benefit from:
- Payment reminders
- Account support
- Restructuring options where available
- Financial education
- Human review
This changes AI from an underwriting tool into a complete credit-risk management platform.
AI and Responsible POS Lending
A high approval rate is not necessarily the objective of a responsible financing platform.
Likewise, a low default rate alone does not prove that an AI system is making good decisions.
A lender should evaluate multiple outcomes.
| Business metric | Risk / consumer metric |
|---|---|
| Approval rate | Delinquency rate |
| Conversion rate | Default rate |
| Merchant revenue | Affordability outcomes |
| Portfolio yield | Complaint rate |
| Loss rate | Adverse-action accuracy |
| Customer lifetime value | Fairness and outcome monitoring |
AI POS Financing Maturity Model
| Stage | Capability | Main characteristic |
|---|---|---|
| 1. Traditional | Rules and conventional scoring | Limited automation |
| 2. ML scoring | Machine-learning risk prediction | Improved pattern detection |
| 3. Real-time AI | Live decisioning | Instant underwriting |
| 4. Contextual lending | Customer + transaction + exposure | Context-aware decisions |
| 5. Adaptive risk platform | Continuous monitoring and model adaptation | Dynamic risk management |
| 6. AI-native lending | Integrated underwriting, fraud, affordability and monitoring | End-to-end intelligent credit infrastructure |
Implementation Roadmap
Phase 1: Data Foundation
Build a reliable data architecture before deploying sophisticated models.
- Centralize application data
- Integrate permitted credit data
- Capture transaction-level information
- Create consistent customer identifiers
- Establish data-quality monitoring
Phase 2: Baseline Risk Model
Develop a transparent baseline model before moving to highly complex machine learning.
The baseline provides a benchmark against which more advanced models can be tested.
Phase 3: Machine Learning
Introduce models such as gradient boosting, random forests, neural networks, or other validated approaches where appropriate.
The objective should be measurable improvement over the baseline rather than simply adopting a more complex algorithm.
Phase 4: Explainability and Governance
Build reason-code generation, model documentation, validation, fairness testing, and adverse-action processes into the system.
Do not leave these components until after deployment.
Phase 5: Real-Time Decisioning
Connect the model to the POS checkout environment.
The system should have clear latency targets and failure-handling rules.
If the AI system becomes unavailable, the platform should have a defined fallback process rather than making uncontrolled decisions.
Phase 6: Continuous Monitoring
Monitor:
- Default performance
- Approval rates
- Model drift
- Data drift
- Fraud rates
- Customer complaints
- Adverse-action accuracy
- Fairness indicators
Expert Recommendation
The strongest approach to AI-powered POS financing is not to build the most complicated possible credit model.
Instead, build a multi-layer risk decision platform.
The AI model should estimate risk, while independent policy and governance layers determine how that risk is converted into a lending decision.
The recommended architecture is:
- AI prediction: Estimate default, delinquency, fraud and affordability risk
- Policy engine: Apply lending rules and product constraints
- Explainability layer: Generate accurate principal reasons for adverse decisions
- Fraud engine: Detect identity and transaction anomalies separately from credit risk
- Exposure engine: Evaluate existing obligations and loan stacking where data is available
- Monitoring engine: Detect model and portfolio deterioration
- Governance layer: Control validation, compliance, audit and model changes
The system should optimize for risk-adjusted lending quality, not simply approval volume.
Future Predictions: 2027–2030
2027: Real-Time Credit Risk Will Become More Contextual
POS lenders will increasingly move from static credit scores toward contextual risk assessment.
The decision may combine:
Customer + transaction + exposure + affordability + fraud + current behavior.
The model will not necessarily replace traditional credit information. Instead, it will combine multiple signals to create a more complete risk picture.
2028: Loan-Stacking Detection Will Become More Important
The CFPB’s research on simultaneous BNPL use demonstrates why individual transaction underwriting can be incomplete.
As embedded credit expands, lenders will increasingly need better ways to understand aggregate consumer exposure.
AI can help identify patterns across repeated applications and obligations where the necessary data is legally and operationally available.
2029: Explainable AI Will Become a Core Lending Infrastructure Layer
Explainability will increasingly be built into credit platforms from the beginning rather than added after model development.
A production AI lending platform will likely need:
- Model explanations.
- Reason codes.
- Decision logs.
- Feature lineage.
- Model-version tracking.
- Validation records.
2030: AI Lending Platforms Will Become Multi-Model Systems
Instead of one giant credit model, lenders are likely to use specialized models for different decisions.
A future POS platform could contain:
+
Fraud Model
+
Credit Model
+
Affordability Model
+
Exposure Model
+
Early Warning Model↓
Unified Risk Decision Engine
This modular approach can make the system easier to monitor and update.
Potential Startup Opportunities
AI-powered POS financing creates opportunities for fintech companies beyond building another BNPL checkout widget.
- AI Underwriting APIs: Real-time credit-risk scoring for merchants and lenders.
- Explainable Credit APIs: Model explanations and adverse-action reason generation.
- AI Affordability Engines: Real-time payment-capacity assessment.
- BNPL Exposure Intelligence: Tools for identifying multiple financing obligations.
- Merchant Risk Platforms: Merchant-level fraud and credit-risk intelligence.
- AI Collections: Early-warning and repayment-risk prioritization.
- Model Monitoring Platforms: AI model drift and performance monitoring for lenders.
- Fairness Testing Platforms: Automated monitoring of credit-model outcomes.
- Embedded Lending Infrastructure: APIs connecting checkout systems, lenders, fraud systems and AI risk engines.
Key KPIs for AI POS Financing
| KPI | Why it matters |
|---|---|
| Approval rate | Measures access to financing |
| Default rate | Measures credit losses |
| Delinquency rate | Identifies repayment deterioration |
| Fraud loss rate | Measures fraud-related losses |
| Decision latency | Measures checkout speed |
| Expected loss | Supports portfolio economics |
| Model stability | Tracks performance over time |
| Explanation accuracy | Ensures reasons accurately represent the decision |
| Customer complaints | Identifies customer-impact problems |
Frequently Asked Questions
What is AI in POS financing?
AI in POS financing uses machine learning, statistical models, and related AI technologies to evaluate credit risk, fraud risk, affordability, customer behavior, and transaction characteristics during a purchase.
Is BNPL the same as POS financing?
No. BNPL is one common type of POS financing, but POS financing can also include longer-term installment loans and other credit products offered during checkout.
How does AI assess POS credit risk?
AI can analyze credit information, transaction behavior, repayment history, permitted alternative data, application characteristics, fraud signals, and existing exposure to estimate repayment and other risks.
Can AI approve POS financing instantly?
Yes. AI-based decision engines can be designed for real-time or near-real-time underwriting. However, speed should not replace affordability checks, fraud controls, explainability, or applicable compliance requirements.
Can AI reduce loan defaults?
Research indicates that machine-learning models can improve credit-risk prediction in certain datasets and settings. However, performance varies by dataset, model, population, market conditions, and implementation. Historical model performance should not be treated as a guarantee of future results.
Why is explainable AI important in POS lending?
Credit decisions can have significant effects on consumers. In the United States, applicable credit laws require creditors to provide specific reasons for certain adverse actions, and the CFPB has stated that complex AI or machine-learning systems do not remove these requirements.
What is loan stacking in BNPL?
Loan stacking occurs when a consumer has multiple BNPL or other credit obligations at the same time. It can make risk assessment more difficult when individual lenders cannot see the customer’s complete borrowing exposure.
Should POS financing use alternative data?
Alternative data can potentially improve credit assessment, especially for customers with limited traditional credit histories. However, each data source should be evaluated for predictive value, legality, privacy, accuracy, fairness, and explainability before deployment.
What is the biggest AI risk in POS financing?
One major risk is making fast credit decisions using models that are inaccurate, biased, poorly monitored, or difficult to explain. Data quality, model drift, fraud, privacy, and regulatory compliance are also important risks.
Final Perspective
AI is transforming POS financing from a relatively simple checkout-credit decision into a broader, real-time risk-management problem.
The traditional question was:
“Does this customer qualify for financing?”
The AI-enabled question is much broader:
“What is the customer’s current credit risk, affordability, fraud risk, transaction risk, existing exposure, and expected repayment behavior?”
That distinction is critical. Research increasingly shows that machine learning can improve credit-risk prediction and extract valuable insights from transaction and alternative data. At the same time, recent studies highlight that the field still faces major gaps regarding transparency, fairness, real-time adaptation, governance, and operational deployment.
Furthermore, the CFPB’s BNPL research provides another vital lesson: because a customer may hold multiple simultaneous financing obligations, evaluating every purchase in complete isolation can easily miss hidden underlying risk.
For fintech companies, this means the future of POS financing is unlikely to rely on a single credit score. Instead, the emerging architecture combines multiple specialized layers:
-
AI credit scoring
-
Fraud intelligence
-
Affordability assessment
-
Transaction intelligence
-
Exposure monitoring
-
Explainable AI
-
Real-time decisioning
-
Post-origination risk monitoring
The strongest systems also clearly separate prediction from policy:
-
The AI model estimates risk
-
The policy engine determines what the lender is willing to do with that risk
-
The governance layer verifies that the entire process remains explainable, monitored, documented, and compliant
This separation is especially important because deploying more complex AI does not automatically translate to better lending outcomes. Ultimately, the goal is a financing platform capable of making instant decisions while rigorously maintaining accuracy, transparency, affordability safeguards, fraud protection, and responsible risk management.
Research Sources
- Expert Systems with Applications: A comprehensive literature review on AI-based credit assessment in digital lending
- Journal of Banking & Finance: Consumer credit-risk models via machine-learning algorithms
- Buy Now, Pay Later: AI, Inherent Tensions, and Implications
- CFPB: Consumer Use of Buy Now, Pay Later and Other Unsecured Debt
- Knowledge-Based Systems: Demystifying deep credit models in e-commerce lending
- Computational Economics: Machine Learning XAI for Early Loan Default Prediction
- CFPB: Research on BNPL borrowers, simultaneous loans and credit balances
- CFPB Circular 2022-03: Adverse action notification requirements for complex algorithms
- CFPB Supervisory Highlights: Advanced Technologies, 2025
- OCC Bulletin 2026-13: Revised Model Risk Management Guidance
- CFPB: Credit access, alternative data and machine learning in underwriting
- CFPB: What is a Buy Now, Pay Later loan?
Leave a Reply