Primary topic: AI in Telematics-Based Insurance Pricing
Research focus: Usage-Based Insurance (UBI), AI risk scoring, driving behavior analytics, dynamic premiums, actuarial modeling, customer retention, fraud detection, privacy, fairness, governance, legacy modernization, and the future of intelligent motor insurance.
What Is Telematics-Based Insurance Pricing?
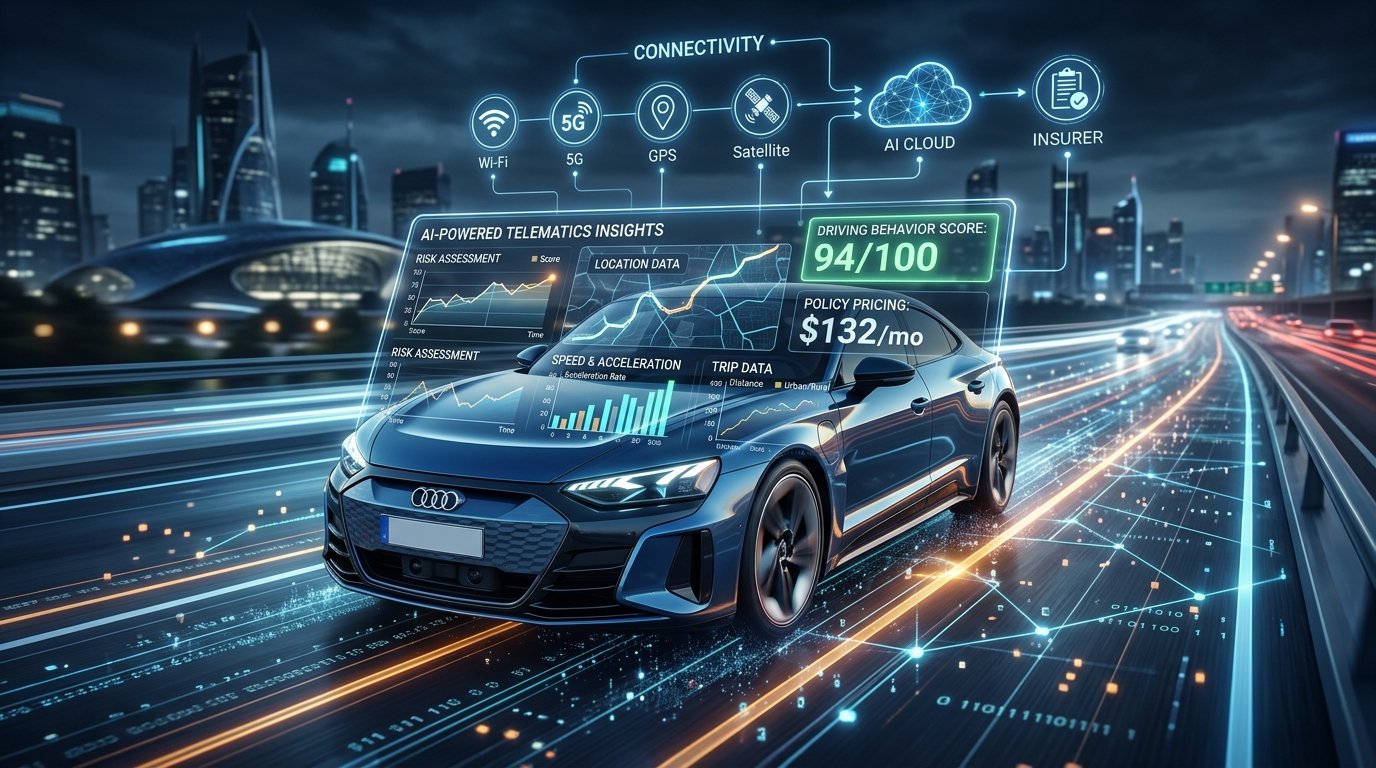
Telematics-based insurance uses connected technology to collect information about how a vehicle is used and how a person drives. Insurers can use this information as part of Usage-Based Insurance, commonly called UBI. Depending on the product, a telematics system may collect mileage, speed, acceleration, braking, cornering, time of travel, road type, location, and other vehicle or smartphone signals.
The basic idea is simple: instead of estimating risk only from historical information about groups of drivers, insurers can also observe actual driving exposure and behavior. A low-mileage driver, for example, may have a different exposure profile from someone who drives thousands of kilometers every month. Similarly, repeated aggressive driving patterns may provide information that cannot be captured from a conventional policy application alone.
The role of AI begins after the data is collected. A telematics platform can generate millions of individual observations, but insurers need models that can determine which signals matter, how they interact, whether they predict future claims, and whether those relationships remain stable over time.
The National Association of Insurance Commissioners describes telematics as a technology that can collect driving information such as mileage, time of day, location, acceleration, braking, and cornering for insurance purposes.
Official source: National Association of Insurance Commissioners — Telematics
How insurance pricing is evolving
Traditional pricing
- Historical claims
- Driver characteristics
- Vehicle information
- Location
- Prior driving history
Telematics pricing
- Mileage
- Speed
- Braking
- Acceleration
- Cornering
- Time and location
AI-powered pricing
- Behavioral patterns
- Contextual risk
- Claim prediction
- Dynamic risk scores
- Personalized recommendations
Why AI Is Becoming Important in Telematics Pricing
A basic UBI program can calculate a score from predefined rules. For example, an insurer might assign points for hard braking, speeding, rapid acceleration, or night driving. This approach is relatively easy to understand, but it may oversimplify the relationship between driving behavior and accident risk.
AI can analyze multiple signals together and identify more complex patterns. A hard-braking event does not necessarily mean the same thing in every situation. Emergency braking in heavy traffic can have a different meaning from repeated hard braking combined with high-speed driving on a particular road type.
This makes contextual analysis important. Modern telematics models can examine behavior alongside exposure, road environment, time of day, mileage, and other available variables. The objective is not simply to count risky events but to estimate the probability and potential cost of future insurance losses.
- Behavioral modeling: identifies repeated driving patterns instead of isolated events.
- Exposure modeling: considers how much and where a customer drives.
- Contextual modeling: considers factors such as road type and time of day.
- Predictive modeling: estimates future claim frequency or severity.
- Personalization: creates individual risk profiles using observed behavior.
- Prevention: identifies patterns that can be addressed before a claim occurs.
Research Study: 19,214 Drivers and 181.4 Million Kilometers
One of the most useful recent studies was published in Heliyon in 2024. Researchers analyzed 19,214 individual drivers over 55 weeks and examined a cumulative driving distance of approximately 181.4 million kilometers.
The researchers developed predictive models for weekly accident frequency using telematics information. The dataset included behavioral variables such as speeding events as well as contextual variables including road type and time of day.
The study found that behavioral traits, particularly excessive-speed events, and contextual information contributed useful information for insurance ratemaking. The researchers also argued that telematics data can support regularly updated driving-risk scores because information from the previous week can help predict future accident occurrence.
This finding is important because it supports a shift away from treating telematics as a one-time discount calculation. If risk information changes over time, insurers can potentially use a dynamic model that updates the driver’s risk representation as new data becomes available.
What this means for insurers:
- Weekly or periodic risk scoring may be technically possible.
- Road type can add context to driving behavior.
- Time of day can contribute to risk prediction.
- Speeding patterns can become useful predictive features.
- Continuous telematics data can support more responsive pricing models.
Original research: Pricing weekly motor insurance drivers’ with behavioral and contextual telematics data — Full Research Paper
PubMed record: PubMed — Pricing weekly motor insurance drivers’ with behavioral and contextual telematics data
Research Study: AI and Boosted Trees for Insurance Claim Frequency
A 2022 study published in Insurance: Mathematics and Economics examined how machine learning could be combined with traditional actuarial modeling for UBI claim-frequency prediction.
The researchers focused on a major challenge in telematics pricing: driving data contains a large number of variables, and those variables can interact in complex ways. Traditional generalized linear models can be useful, but they may not capture every nonlinear relationship between driving behavior and insurance losses.
The researchers therefore developed a framework using boosted trees together with zero-inflated Poisson and zero-inflated negative-binomial actuarial distributions. The study reported high predictive accuracy on UBI and French motor third-party liability datasets and also examined the interpretability of the models.
The important lesson is that AI does not need to operate separately from actuarial science. A hybrid actuarial-machine-learning architecture can use the strengths of both approaches.
Why this matters:
- Insurance claim frequency is naturally suited to actuarial probability models.
- Telematics creates many behavioral variables and interactions.
- Boosted trees can capture nonlinear relationships.
- Hybrid models can preserve insurance-specific statistical structure.
- Interpretability remains important when AI affects pricing.
Original research: Actuarial intelligence in auto insurance: Claim frequency modeling with driving behavior features and improved boosted trees — ScienceDirect
Research Study: Telematics-Based Classification Ratemaking
A 2019 study published in Decision Support Systems proposed a complete classification-ratemaking framework for Usage-Based Insurance. The researchers investigated a broad set of driving behavior variables and examined how they could contribute to automobile insurance pricing.
The study combined data-binning methods with machine-learning techniques. According to the paper, this combination improved both the accuracy and interpretability of pricing.
This is especially relevant to real insurance systems because a pricing model cannot be evaluated only by predictive accuracy. Insurers also need to understand how rating factors affect the resulting premium and whether those relationships can be explained and defended.
The research also reinforces an important concept: telematics variables can provide more direct information about driving behavior than many conventional demographic variables, but they still need to be carefully selected, validated, and incorporated into a regulated pricing process.
Original research: Automobile insurance classification ratemaking based on telematics driving data — ScienceDirect
Research Study: Dynamically Updating Motor Insurance Prices
Another important 2022 study examined the added value of dynamically updating motor insurance prices using telematics-collected driving behavior. The researchers worked with a motor third-party liability portfolio and followed young policyholders over a three-year period.
The study considered total mileage, distance driven on different road types, different time slots, harsh acceleration, harsh braking, harsh cornering, and lateral movement events. A baseline pricing model was first established using conventional insurance information, after which telematics data was used to update the price for young drivers.
The researchers found evidence of improved risk classification and examined business implications including expected profits and retention rates. This demonstrates why telematics pricing should be viewed as a business model rather than simply an AI model.
A technically accurate risk model can still produce poor commercial outcomes if customers do not understand it, if pricing becomes excessively aggressive, or if the product causes undesirable customer churn.
Original research: The added value of dynamically updating motor insurance prices with telematics collected driving behavior data — ScienceDirect
Research Study: Customer Retention Must Be Part of AI Pricing
A 2025 study in Insurance: Mathematics and Economics takes the telematics pricing problem one step further. The researchers argue that overly discriminatory UBI pricing can push high-risk customers away even when those customers could potentially improve their driving behavior.
The researchers developed a UBI pricing model that combines driving-risk assessment with customer price sensitivity and retention. The model uses targeted discounts for customers who may otherwise leave and uses SHAP-based interpretation to identify the insurance cost associated with different driving behaviors.
The study used empirical data from a major Chinese auto insurer and reported higher insurer profits than a UBI pricing approach that did not account for customer retention.
The significance of this research goes beyond discounts. It suggests that future AI pricing systems may need to optimize several objectives simultaneously rather than simply maximizing risk differentiation.
- Expected loss
- Premium level
- Customer price sensitivity
- Retention probability
- Behavior improvement
- Long-term portfolio economics
Original research: A usage-based insurance (UBI) pricing model considering customer retention — ScienceDirect
Research Study: UBI and Customer Coverage Decisions
A 2024 study published in the Journal of Risk and Insurance examined how Usage-Based Insurance affects customers’ insurance coverage choices. The research used a large sample of 135,540 customers.
The study found that UBI customers were more likely than non-UBI customers to change their coverage at the first annual renewal. The researchers also reported that UBI customers received an average permanent discount of approximately 12% in the studied setting. Higher UBI discounts were associated with greater likelihood of increasing coverage and adding comprehensive coverage at the first renewal.
This provides an important commercial insight. Telematics does not only influence the premium. The information customers receive about their own driving behavior can influence how they think about their insurance needs and how they interact with the insurer.
For AI product designers, this means the customer dashboard is part of the insurance product. Risk scoring, explanation, feedback, and policy recommendations should not be treated as disconnected components.
Original research: Insurtech, sensor data, and changes in customers’ coverage choices: Evidence from usage-based automobile insurance — Wiley
Research Study: Systematic Review of IoT-Enabled Insurance
A major 2025 systematic literature review examined the broader relationship between IoT-enabled risk prevention and insurance. The researchers identified 5,764 records and ultimately analyzed 56 academic studies and 18 practitioner studies.
The review found that connected technologies can expand insurance beyond traditional risk financing by enabling risk monitoring, prevention, personalized pricing, incentives, and real-time services. At the same time, the authors identified additional costs and risks, including technology expenses, privacy loss, cybersecurity risks, and customers’ willingness to share data.
The researchers describe a changing role for insurers: from organizations that primarily finance losses toward organizations that can also participate in risk management and prevention.
This is one of the most important findings for the future of telematics insurance. The value of AI may ultimately come not only from better pricing but from preventing losses before they happen.
Original systematic review: On IoT-enabled risk prevention and insurance: A systematic literature review — Wiley
Research evidence dashboard
Drivers in the 2024 weekly accident-frequency study
Cumulative driving distance analyzed
Customers in the UBI coverage-choice study
Academic and practitioner studies in the 2025 IoT insurance review
Average permanent UBI discount reported in the coverage-choice study
What Telematics Data Should AI Analyze?
The objective should not be to collect the maximum amount of data. The better approach is to collect and process the variables that have a defensible relationship with insurance risk and that are appropriate for the product and jurisdiction.
| Telematics signal | What it represents | Potential AI use |
|---|---|---|
| Mileage | Driving exposure | Exposure-adjusted risk |
| Speed | Driving intensity | Persistent speeding patterns |
| Acceleration | Driving style | Behavior classification |
| Braking | Potential emergency events | Repeated-risk detection |
| Cornering | Vehicle handling | Driving-style analysis |
| Time of day | Temporal exposure | Contextual prediction |
| Road type | Driving environment | Context-aware modeling |
| Location | Geographic exposure | Geographic risk modeling |
Context-Aware AI Is Better Than Simple Driver Scores
A simplistic telematics score might count hard braking, speeding, acceleration, and cornering events. AI can go further by asking how those events occurred and whether they form a repeated pattern.
For example, one hard-braking event may be caused by avoiding another vehicle. Ten hard-braking events over a very short driving distance may represent a different pattern. The same number of events over a much larger exposure may also have a different statistical meaning.
This is why exposure, context, and behavior need to be analyzed together rather than assigning the same penalty to every isolated event.
Example of contextual risk analysis
- Hard braking + heavy traffic + urban roads → context needs to be considered before assigning risk.
- Repeated hard braking + high speed + short exposure → potentially stronger risk signal.
- High speed + highway + short duration → different context from high speed in a residential area.
- Repeated risky behavior across several weeks → potentially stronger signal than one isolated event.
AI Models Used in Telematics Insurance
Different machine-learning techniques are suitable for different parts of the telematics problem. There is no single AI model that should automatically be used for every insurer or every product.
- Gradient boosting: useful for structured insurance and telematics variables.
- Random forests: useful for nonlinear relationships and feature analysis.
- Neural networks: useful for complex and high-volume sensor data.
- Sequence models: useful for understanding driving behavior over time.
- Clustering: useful for identifying different driving profiles.
- Anomaly detection: useful for unusual behavior and potential fraud signals.
- Survival models: useful for time-to-claim analysis.
- Graph analytics: useful when drivers, vehicles, claims, devices, locations, and accounts form connected patterns.
- Explainable AI: useful when insurers need to understand why a model produced a particular risk estimate.
From Raw Telematics Data to an Insurance Premium
Connected Vehicle / Smartphone / OBD Device
↓
Telematics Data Collection
↓
Data Quality & Normalization
↓
Feature Engineering
↓
AI Risk Model
↓
Claim Frequency / Severity Prediction
↓
Actuarial Pricing Layer
↓
Approved Premium Calculation
↓
Customer Feedback & Risk Prevention
A critical design principle is to separate risk prediction from final pricing. The machine-learning model can estimate claim probability, expected frequency, severity, or another approved risk metric. An actuarial and business layer can then incorporate deductibles, coverage, expenses, regulatory requirements, portfolio objectives, and other approved pricing factors.
Dynamic Insurance Pricing
Telematics allows insurers to create several different UBI structures. Some products focus on mileage, while others focus on driving behavior. More advanced products can combine both approaches.
| Model | Main signal | Typical objective |
|---|---|---|
| Pay-As-You-Drive | Mileage | Price according to driving exposure |
| Pay-How-You-Drive | Driving behavior | Differentiate driving risk |
| Hybrid UBI | Mileage + behavior | Combine exposure and behavior |
| Dynamic UBI | Continuously updated behavior | Adjust risk representation over time |
AI Can Turn Insurance Into a Risk-Prevention Service
The most interesting long-term opportunity is to use telematics not only to price risk but also to help reduce it. If an AI system detects a repeated pattern, the insurer can provide feedback before that behavior results in a claim.
- Identify repeated speeding patterns.
- Detect frequent harsh acceleration.
- Identify repeated hard braking.
- Identify risky driving periods.
- Provide personalized driving recommendations.
- Track whether behavior improves after feedback.
- Use behavioral improvement as an input into future customer engagement.
AI prevention loop
Privacy: The Biggest Trust Challenge
Telematics creates a different privacy profile from traditional insurance because driving data can reveal patterns about where, when, and how a vehicle is used. Smartphone-based telematics can create additional privacy considerations because the technology may involve device permissions and location information.
The 2025 systematic review of IoT-enabled insurance identified privacy loss, cybersecurity risk, technology costs, and willingness to share data as important parts of the connected-insurance cost-benefit equation.
Original research: 2025 systematic review — On IoT-enabled risk prevention and insurance
- Explain what data is collected.
- Explain why each data category is required.
- Define retention periods.
- Restrict employee access to sensitive raw data.
- Encrypt data during transmission and storage.
- Monitor third-party telematics providers.
- Maintain clear customer consent and privacy documentation.
Fairness and Algorithmic Bias
More data does not automatically mean a fairer pricing system. Bias can enter through incomplete data, device differences, geographic coverage, vehicle technology, feature selection, historical claims, model architecture, or business rules.
For example, customers with newer connected vehicles may produce richer telemetry than customers using older vehicles. Smartphone-based systems can also produce different data depending on device capabilities, permissions, connectivity, and customer behavior.
A responsible insurer should therefore test whether model performance remains stable across relevant customer groups and data conditions. Fairness should be treated as a model lifecycle issue rather than a one-time review.
AI Governance and Insurance Regulation
AI-based insurance pricing operates inside a regulated industry. The model therefore needs more than technical accuracy. Insurers also need governance around data, model development, validation, documentation, explainability, cybersecurity, human oversight, and customer outcomes.
EIOPA’s 2025 Opinion on AI governance and risk management specifically addresses AI use in insurance and highlights data governance, record-keeping, fairness, cybersecurity, explainability, and human oversight.
Official regulatory source: EIOPA — Opinion on Artificial Intelligence Governance and Risk Management
EIOPA has also reported that AI is increasingly being used across the insurance value chain, including pricing, underwriting, claims management, and fraud detection. Its 2025 commentary notes both the potential for more precise segmentation and the risk that highly personalized pricing could create access and fairness concerns.
Official source: EIOPA — Scaling AI in insurance: striking the right regulatory balance
Expert quotation: EIOPA describes AI as having a role in the “digital transformation of the insurance sector,” while emphasizing the need to balance innovation with governance and consumer protection.
Human Oversight Should Remain in the Pricing System
An AI system should not become an unexplained authority over insurance pricing. Human oversight is important when the model produces unexpected results, data quality is poor, a customer disputes an outcome, or model performance changes over time.
| AI function | Human responsibility |
|---|---|
| Risk prediction | Validate accuracy, calibration, and limitations |
| Feature selection | Review relevance, fairness, and regulatory suitability |
| Pricing | Apply approved actuarial and business rules |
| Customer dispute | Provide review and escalation |
| Model drift | Approve retraining, recalibration, or replacement |
AI for Telematics Fraud Detection
The same telematics infrastructure can support claims and fraud analytics. Vehicle movement, timestamps, location information, mileage, braking patterns, and other sensor signals can provide additional evidence during claim investigation.
AI can compare reported accident information with available vehicle data and identify inconsistencies that deserve investigation. However, an anomaly should not automatically be treated as proof of fraud. False positives can harm customers and create operational and regulatory problems.
- Use AI to prioritize suspicious claims for investigation.
- Combine telematics with claims and policy data.
- Maintain human review for material fraud decisions.
- Record the evidence supporting investigation decisions.
- Monitor false-positive rates.
Real-Time AI Architecture for Telematics Insurance
Connected Vehicle
↓
Telematics Gateway
↓
Streaming Data Platform
↓
Data Quality + Identity Resolution
↓
Feature Store
↓
AI Risk Engine
↓
Explainability + Fairness Layer
↓
Actuarial Pricing Engine
↓
Policy Administration System
↓
Customer App / Agent Portal
A production architecture should also include model versioning, audit logs, security controls, consent management, data lineage, model monitoring, alerting, retraining workflows, and disaster recovery.
Legacy Insurance Modernization
Many insurers still operate core policy, billing, and claims systems that were not designed for continuous telematics data. Replacing these platforms completely can be expensive and operationally risky. A more practical approach is often to introduce an AI and telematics layer around the existing systems.
- Connect vehicle and smartphone telematics through secure APIs.
- Create a modern data platform for telemetry.
- Build a feature store for insurance-ready driving variables.
- Deploy the AI scoring engine independently from the legacy rating system.
- Send approved risk outputs into existing pricing workflows.
- Introduce customer-facing dashboards separately from the core policy system.
- Modernize incrementally instead of replacing every legacy component at once.
High-Value AI Use Cases
| Use case | Potential value | Important control |
|---|---|---|
| AI risk scoring | More granular risk classification | Validation and calibration |
| Mileage pricing | Better exposure measurement | Reliable mileage data |
| Behavior coaching | Potential risk prevention | Customer acceptance |
| Claim prediction | Better portfolio analytics | Model drift monitoring |
| Fraud analytics | Earlier investigation | Human review |
| Retention modeling | Better long-term customer economics | Customer fairness |
Risk Matrix
| Risk | Potential impact | Recommended control |
|---|---|---|
| Privacy breach | High | Encryption, minimization, access controls |
| Algorithmic bias | High | Fairness testing and independent validation |
| Sensor error | Medium | Continuous data-quality monitoring |
| Model drift | High | Continuous monitoring and recalibration |
| Customer confusion | Medium | Clear explanations and dashboards |
| Third-party dependency | Medium | Vendor governance and fallback systems |
Expert Recommendation: Use a Hybrid Actuarial-AI Model
The research points toward a practical architecture in which machine learning enhances actuarial pricing instead of attempting to replace it. The AI model can discover complex relationships in telematics data, while actuarial models and approved pricing rules remain responsible for translating risk estimates into insurance prices.
This hybrid approach also provides a clearer path for legacy modernization. An insurer can introduce AI as a separate risk-scoring layer, validate its performance, and gradually connect it to existing pricing infrastructure.
- Use AI for risk prediction and behavioral analysis.
- Keep actuarial expertise in the pricing lifecycle.
- Use explainable methods where pricing impact is significant.
- Validate models against established actuarial baselines.
- Test models across different driving environments and vehicle types.
- Monitor customer outcomes as well as model accuracy.
- Provide understandable explanations for telematics scores.
- Maintain formal model approval and retirement procedures.
AI Maturity Model for Telematics Insurance
Level 1: Data CollectionBasic mileage and driving-event collection.
Level 2: Rule-Based UBIFixed thresholds and predefined discounts.
Level 3: Predictive AIMachine-learning risk prediction.
Level 4: Contextual AIBehavior, exposure, and environmental context.
Level 5: Adaptive InsuranceContinuous prediction, prevention, engagement, and pricing.
Future Predictions for 2027–2030
Telematics Will Move Beyond Simple Discounts
The first generation of UBI products often focused on rewarding customers for lower mileage or safer driving. The next stage is likely to combine pricing, risk prediction, prevention, claims, and customer engagement into a single connected system.
Contextual Risk Will Become More Important
Future AI systems are likely to place greater emphasis on the context surrounding driving events. Instead of treating every hard brake or speeding event as identical, models will increasingly consider exposure, road type, time, frequency, duration, and historical behavior.
Connected Vehicles Will Become an Increasingly Important Data Source
As vehicle connectivity expands, insurers can receive richer information directly from vehicle systems rather than depending entirely on smartphone applications or aftermarket devices. This can improve data quality but will also increase questions about data ownership, interoperability, consent, and third-party access.
Explainability Will Become Part of the Customer Experience
A customer who receives a different premium because of telematics will reasonably want to understand why. Future UBI products will therefore need customer-facing explanations that translate complex AI signals into understandable driving insights.
Privacy-Preserving Analytics Will Become More Important
Insurers will have a strong incentive to extract useful risk signals without retaining unnecessary raw location histories. Data minimization, aggregation, controlled access, privacy-enhancing technologies, and stronger governance can become important parts of future telematics architectures.
Insurance Will Become More Preventive
The long-term opportunity is to reduce the number and severity of losses rather than simply predicting them. AI can help identify risky patterns, provide feedback, and measure behavioral change while maintaining appropriate separation between safety interventions and pricing decisions.
Startup Opportunities
The telematics market creates opportunities for technology companies that can solve specific infrastructure and AI problems for insurers.
- Telematics AI risk engine: Convert raw vehicle data into insurance-ready risk features.
- Explainable UBI platform: Generate understandable explanations for risk scores and pricing factors.
- Telematics fraud intelligence: Compare accident claims with observed vehicle behavior.
- Fleet insurance AI: Analyze commercial fleet behavior and risk.
- Driver coaching platform: Deliver personalized feedback based on repeated behavior.
- Data-quality platform: Detect missing, corrupted, manipulated, or inconsistent sensor information.
- AI governance platform: Monitor model performance, fairness, drift, documentation, and auditability.
- Legacy integration middleware: Connect modern telematics platforms with traditional policy systems.
Implementation Roadmap
Phase A: Data foundation
- Identify telematics sources.
- Define data ownership and consent requirements.
- Build secure data ingestion.
- Establish data-quality controls.
Phase B: AI risk modeling
- Define claim-frequency and severity targets.
- Build a traditional actuarial baseline.
- Test machine-learning models against the baseline.
- Perform fairness, stability, and calibration testing.
Phase C: Controlled pilot
- Launch with a limited customer segment.
- Measure risk prediction.
- Measure customer response.
- Monitor complaints and retention.
Phase D: Production integration
- Connect the AI risk engine with approved pricing systems.
- Implement audit logs and model monitoring.
- Create customer-facing explanations.
- Establish human escalation procedures.
Phase E: Continuous optimization
- Monitor model drift.
- Retrain when evidence supports it.
- Review fairness and regulatory requirements.
- Expand into claims, fraud, and prevention.
Key KPIs
| Category | Important KPIs |
|---|---|
| Risk | Claim frequency, severity, loss ratio, calibration |
| AI | Precision, recall, calibration, drift, stability |
| Customer | Retention, complaints, adoption, engagement |
| Prevention | Risk-event frequency and behavior improvement |
| Governance | Model reviews, audit findings, fairness tests |
| Technology | Data availability, API uptime, processing latency |
Frequently Asked Questions
What is AI in telematics-based insurance pricing?
It is the use of machine learning and related AI methods to analyze connected-vehicle and driving data and estimate insurance risk. The resulting information can support UBI pricing, discounts, underwriting, customer feedback, claims analysis, and fraud investigation.
What data can telematics collect?
Depending on the product, telematics can collect mileage, speed, acceleration, braking, cornering, time of day, location, and other vehicle or smartphone signals. The exact data depends on the technology, insurer, product, customer consent, and applicable regulation.
Can AI make insurance pricing more accurate?
Research indicates that telematics variables can provide useful information for risk classification and accident-frequency prediction. Accuracy depends on data quality, model design, validation, population characteristics, and how AI outputs are incorporated into actuarial pricing.
Does telematics always reduce premiums?
No. Some products primarily provide discounts, while others use telematics as one pricing factor among several. The effect on an individual premium depends on product design, observed behavior, exposure, the overall rating structure, and applicable regulation.
Is telematics data a privacy concern?
Yes. Telematics can reveal information about driving behavior and, in some implementations, location. A responsible program should clearly explain what information is collected, why it is collected, how long it is retained, who can access it, and whether it is shared.
Should insurers replace actuaries with AI?
No. AI can improve predictive analysis and identify complex relationships, while actuarial expertise remains important for pricing methodology, validation, uncertainty, portfolio management, regulatory requirements, and interpretation.
Final Perspective
AI in telematics-based insurance pricing represents a significant change in how motor insurers can understand and manage risk. The most important development is not simply the availability of more vehicle data. It is the ability to connect observed driving behavior and exposure with statistical models that can estimate future loss more dynamically.
The research base is increasingly strong. A 2024 study analyzed 19,214 drivers and 181.4 million kilometers of driving data. Research has demonstrated how boosted-tree machine learning can be combined with actuarial claim-frequency models, how telematics can improve classification ratemaking, how dynamic pricing can use observed driving behavior, and how customer retention can be incorporated into UBI pricing.
The 2025 systematic review of 74 academic and practitioner studies also shows that connected insurance is expanding beyond pricing. IoT can support risk prevention, real-time services, incentives, and personalized risk management, while introducing additional challenges around privacy, cybersecurity, technology costs, and willingness to share data.
For insurers, the practical direction is therefore a hybrid actuarial-AI architecture. AI should identify patterns and estimate risk, while actuarial methods, governance controls, regulatory requirements, and human oversight determine how those predictions are used.
For technology companies and startups, the opportunity extends far beyond building another driver-score application. The strongest opportunities are likely to sit around telematics data infrastructure, explainable risk models, fraud analytics, driver coaching, AI governance, privacy-preserving analytics, and integration with legacy insurance systems.
The long-term evolution of UBI can be summarized as measure → predict → explain → prevent → reassess. The insurer of the future may not simply price the risk of a driver. It may continuously understand that risk, communicate it to the customer, and help reduce it while maintaining appropriate fairness, privacy, governance, and actuarial discipline.
Original Research & Official Sources
- Pricing weekly motor insurance drivers’ with behavioral and contextual telematics data — Full Research Paper
- PubMed — Pricing weekly motor insurance drivers’ with behavioral and contextual telematics data
- Actuarial intelligence in auto insurance: Claim frequency modeling with driving behavior features and improved boosted trees — ScienceDirect
- Automobile insurance classification ratemaking based on telematics driving data — ScienceDirect
- The added value of dynamically updating motor insurance prices with telematics collected driving behavior data — ScienceDirect
- A usage-based insurance (UBI) pricing model considering customer retention — ScienceDirect
- Insurtech, sensor data, and changes in customers’ coverage choices — Wiley
- On IoT-enabled risk prevention and insurance: A systematic literature review — Wiley
- Telematics in Insurance: Challenges and Limitations — IEEE Access
- National Association of Insurance Commissioners — Telematics
- EIOPA — Opinion on Artificial Intelligence Governance and Risk Management
- EIOPA — Scaling AI in insurance: striking the right regulatory balance
Leave a Reply