
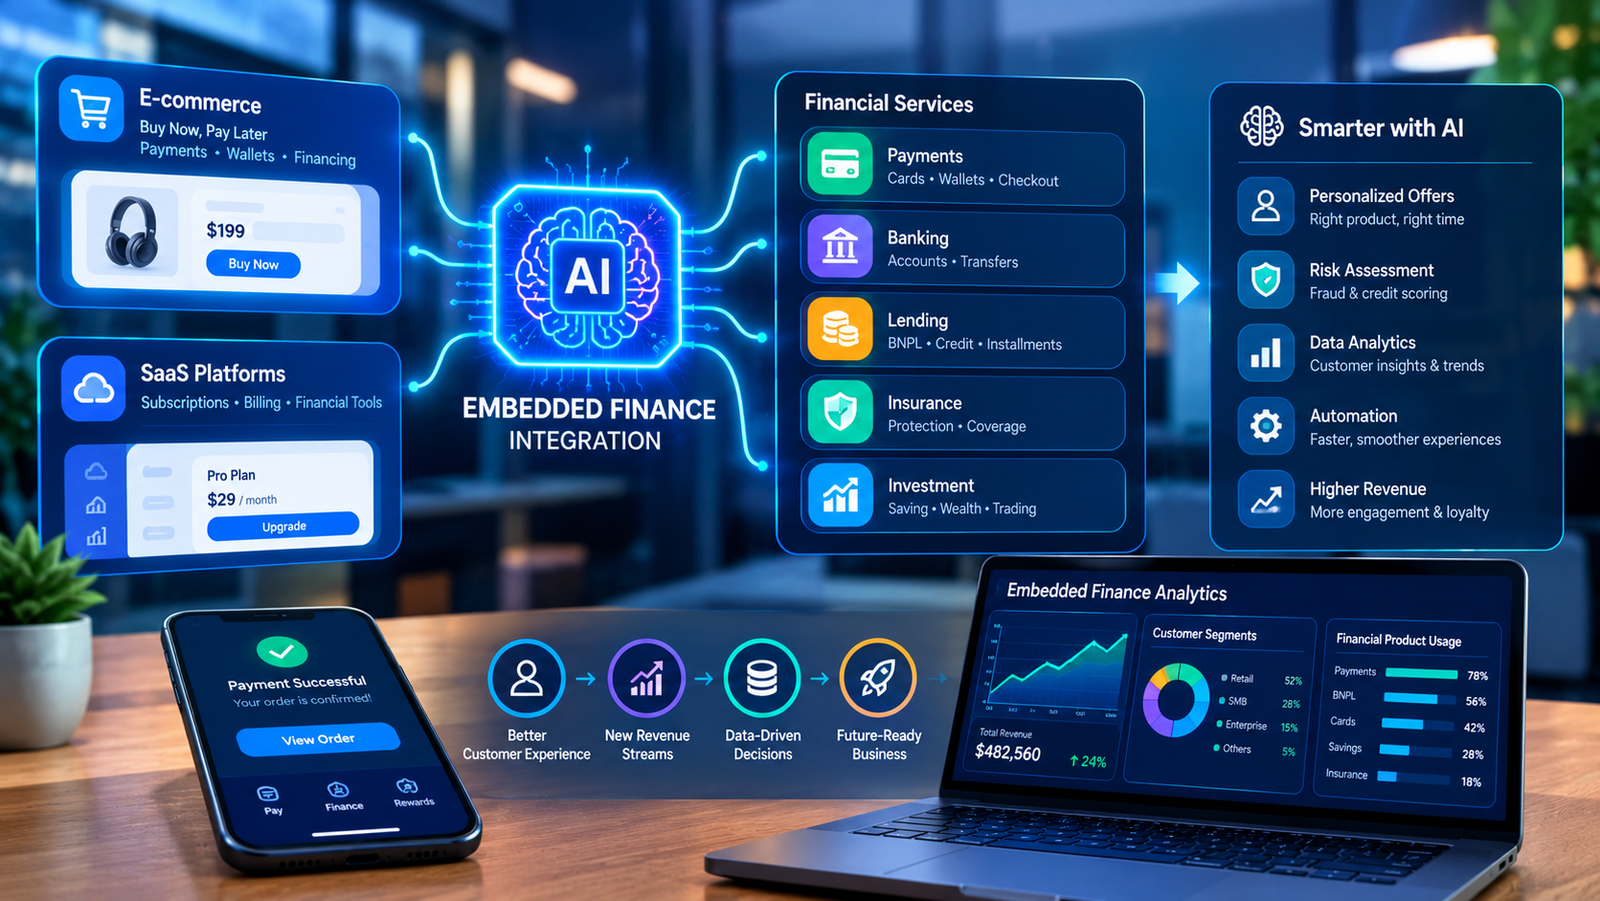
Primary topic: AI in Embedded Finance Integration for Non-Financial Platforms
Research focus: AI-powered embedded payments, e-commerce checkout financing, SaaS banking, merchant cash-flow analytics, credit decisioning, fraud prevention, financial personalization, payment orchestration, lending APIs, financial data integration, and AI governance
What Is AI in Embedded Finance?
Embedded finance means integrating financial products into a non-financial platform so customers can access them without leaving the main product experience. An e-commerce business might offer installment payments at checkout, while a SaaS platform used by small businesses might provide payment acceptance, business accounts, expense management, or working-capital financing.
AI adds intelligence to these services. It can help a platform understand when a customer needs financing, estimate whether a merchant can repay a loan, identify suspicious transactions, forecast upcoming cash requirements, or recommend a suitable payment method. The financial service remains connected to banks, lenders, payment processors, or other regulated partners, but AI helps make the experience more relevant and operationally efficient.
Boston Consulting Group’s 2025 analysis describes vertical SaaS platforms as increasingly important operating systems for small and medium-sized businesses. These platforms already manage activities such as booking, sales, invoicing, and payments, giving them useful context for offering additional financial services. BCG argues that the opportunity depends on product-market fit, merchant relationships, pricing, and the ability to manage risk rather than simply adding more financial products.
Source: BCG, Moving Embedded Finance from Promise to Practice, 2025
Where Embedded Finance Fits Inside Non-Financial Platforms
Embedded finance looks different depending on the platform’s business model. An online retailer sees customer checkout and order data, while a SaaS platform may see recurring invoices, subscriptions, payroll, inventory, and supplier payments. These differences affect which AI applications are useful and which data the platform can responsibly access.
| Platform type | Embedded financial product | Potential AI contribution |
|---|---|---|
| E-commerce | Installments, checkout payments, refunds | Payment selection, fraud detection, affordability signals |
| Vertical SaaS | Merchant accounts, business cards, working capital | Cash-flow forecasting, credit risk, financing timing |
| Marketplaces | Seller payouts, advances, payment accounts | Seller risk, payout anomalies, revenue forecasting |
| B2B procurement | Trade credit, invoice financing, supplier payments | Invoice analysis, payment prediction, credit monitoring |
| Subscription software | Billing, expense tools, cash management | Payment failure prediction, reconciliation, cash planning |
Why AI Changes the Embedded Finance Model
Traditional integrations often focus on making a financial product available through an API. AI can help the platform decide how that product should be presented, which risks require attention, and how the service should respond as the customer’s circumstances change.
For example, an e-commerce platform may know that a customer is buying a high-value item, but it should not assume that the customer needs credit. A more responsible system can present available payment methods clearly, apply the lender’s eligibility rules, and avoid using unrelated or sensitive personal information to pressure the customer into borrowing.
A SaaS platform serving independent retailers may have a different opportunity. If the merchant has consented to the relevant data use, the platform may analyze sales, refunds, invoice payments, seasonal demand, and supplier obligations to estimate working-capital needs. The resulting insight could support a financing application or help the merchant plan payments.
Context
Understand the transaction or business workflow where finance is needed
Intelligence
Use AI to analyze permitted data and identify relevant signals
Financial action
Present an eligible payment, financing, or cash-management option
Control
Apply partner rules, user authorization, monitoring, and audit trails
The value comes from making finance fit the workflow, not from adding AI to every step.
Research Study: AI Credit Assessment in Digital Lending
A 2026 systematic literature review published in Expert Systems with Applications examined 118 peer-reviewed studies on AI-based credit assessment in digital lending, covering research published from 2018 to 2025. The review examined machine-learning and hybrid models, alternative data, real-time learning, explainability, and fairness-oriented governance.
The authors found that ensemble and hybrid deep-learning models were prominent in the literature and often delivered strong predictive performance. Alternative data, including transaction streams and behavioral information, could help assess borrowers with limited traditional credit histories. However, the review also identified unresolved issues around bias, privacy, the transferability of behavioral data across populations, and the practical reliability of explanations generated by methods such as SHAP and LIME.
For embedded finance, the study is relevant because non-financial platforms often hold operational data that conventional lenders do not see in the same detail. A SaaS product may observe invoices and recurring sales, while a marketplace may see completed orders, returns, cancellations, and seller payouts. These signals can add context to a credit assessment, but they do not automatically prove that a borrower is creditworthy.
The review also found that real-time adaptive credit models remain underdeveloped, with limited large-scale treatment of changing data patterns. This matters for platforms whose merchants experience seasonal sales, sudden demand changes, or shifts in payment behavior. A model that was accurate last year may become less reliable when a merchant’s operating conditions change.
What this means for product teams: AI-based underwriting should be designed as a governed credit-assessment capability, not a simple score returned by an API. Teams should validate models on the intended customer population, measure approval and error rates across relevant groups, explain adverse decisions where required, and monitor model performance after launch.
Research Study: Open Banking Payment Data for Loan Screening and Monitoring
A 2026 study in the Journal of Financial Intermediation examined how interoperable payment data can improve loan screening and monitoring. The research linked borrowers’ payment histories with non-bank small-business loans in India and investigated whether payment information adds value beyond conventional credit-bureau data.
The study found that payment histories and credit-bureau information capture different aspects of borrower risk. Payment data primarily reflected real-time repayment ability, while credit-bureau information provided insight into willingness to repay. The sources were therefore complementary rather than interchangeable.
This distinction is highly relevant to embedded finance. A SaaS platform may observe a merchant’s incoming payments, outgoing supplier transfers, and recurring obligations. With appropriate permission and a suitable data-sharing arrangement, these signals may help a lender understand current cash-flow capacity. A credit bureau may provide a different view of the merchant’s previous borrowing and repayment record.
The study also identified distributional trade-offs. Payment-based screening benefited many borrowers, but could disadvantage people with poor credit scores or thin payment records. This is an important warning against assuming that more data always produces fairer lending. A business with a short operating history may have limited payment data even if its future prospects are reasonable.
What this means for product teams: Embedded lending should combine relevant payment information with other suitable evidence. Missing data should not automatically be interpreted as high risk, and platforms should provide alternative assessment routes when the data is incomplete or unsuitable.
Research Study: Graph-Based AI for E-Commerce Fraud Detection
A 2026 study published in IEEE Access investigated e-commerce transaction fraud detection using graph-based feature embeddings combined with conventional machine-learning models. The research addressed a limitation of models that assess each transaction independently: fraudulent activity may become more visible when transactions share devices, IP addresses, payment instruments, or other relationships.
The researchers used a dataset containing 1,472,952 training records and 23,634 test records. They compared models using tabular features alone, end-to-end graph neural networks, and a hybrid approach that combined graph-derived features with traditional transaction data.
The hybrid approach consistently improved on tabular-only baselines in the reported experiments. The best balanced result came from a Random Forest model using graph embeddings, with an accuracy of 0.9688, an F1 score of 0.6091, and a precision-recall AUC of 0.6171. The study noted that the improvement over the strongest tabular baseline was modest, suggesting that graph features were complementary rather than a complete replacement for conventional models.
This is a useful distinction for embedded finance. A checkout platform may see a transaction’s amount, product, payment method, and customer history. A graph-based system can add relationships among accounts, devices, merchants, and payment instruments. These connections may reveal coordinated abuse that is difficult to detect from one transaction at a time.
However, high overall accuracy can be misleading when fraud is rare. Precision, recall, false-positive rates, and the cost of incorrectly blocking legitimate purchases are more useful for evaluating a production system.
What this means for product teams: Use relational AI as an additional signal in fraud decisions. Test it against realistic fraud rates, monitor customer friction, and make sure that the platform can explain why a transaction was blocked or referred for review.
Research Study: Machine Learning for Fintech Fraud and Anomaly Detection
A 2023 study, Safeguarding FinTech Innovations with Machine Learning: Comparative Assessment of Various Approaches, compared machine-learning techniques for identifying anomalies and fraud in fintech environments. Its focus was the protection of digital financial services, where fraudulent activity can harm customers and providers while weakening trust in the platform.
The study is relevant to embedded finance because the non-financial interface does not remove the underlying risks of digital financial transactions. An e-commerce company that embeds payments still needs to detect account takeover, payment abuse, suspicious account behavior, and potentially coordinated fraud. A SaaS platform that offers merchant payouts or business accounts faces related risks around identity, access, and unusual movement of funds.
Machine-learning anomaly detection can help identify behavior that differs from a user’s normal activity or from the patterns of comparable accounts. Yet an anomaly is not necessarily fraud. A merchant may experience an unusually large sales day during a promotion, while a legitimate customer may make a purchase from a new device while traveling.
The practical lesson is to combine anomaly detection with transaction context, known fraud patterns, authentication signals, and review procedures. Models should be evaluated using data that reflects the platform’s actual users and transaction mix.
What this means for product teams: Fraud models should be measured by their ability to reduce financial loss and unnecessary customer friction, not by the number of alerts they generate.
Research Study: AI and the Practical Business Case for Embedded Finance
Boston Consulting Group’s 2025 analysis, Moving Embedded Finance from Promise to Practice, examines the opportunity for vertical SaaS providers to offer more financial services to small and medium-sized businesses. It is an industry analysis rather than a controlled AI experiment, but it helps explain where AI-enabled embedded finance can create commercial value.
BCG notes that many small businesses already use vertical software to run important parts of their operations. These platforms may manage customer relationships, appointments, inventory, invoicing, and payments, creating an established distribution channel for financial products. The analysis emphasizes that providers must offer a compelling value proposition and balance customer experience with capital allocation and risk.
This has a direct implication for AI development. A platform should not build a credit model simply because it has transaction data. It should first identify a specific customer problem, such as unpredictable cash flow, delayed supplier payments, or difficulty accessing working capital. AI is useful when it improves the decision or service that addresses that problem.
For example, a platform used by independent restaurants might combine seasonal revenue patterns, supplier invoices, and payment obligations to help a financing partner assess an application. A field-service SaaS product might help contractors forecast upcoming receivables and expenses. The AI capability is strongest when it is closely tied to the operational context of the platform.
What this means for product teams: Start with a clearly defined customer need and use the platform’s existing workflow as the distribution advantage. Do not assume that more embedded products automatically lead to better retention or profitability.
Source: Boston Consulting Group, Moving Embedded Finance from Promise to Practice, 2025
Research Study: Agentic AI and the Future of Payments
An April 2026 IMF note, How Agentic AI Will Reshape Payments, examines how AI systems that can plan and execute multi-step tasks may affect payment systems. The note focuses on authorization, liquidity, settlement, compliance, and resilience.
The central issue is that AI agents can operate probabilistically, while payment infrastructure requires deterministic controls, clear authorization, reliable settlement, and accountability. An AI agent may be able to identify an invoice, recommend a payment date, or coordinate a workflow, but payment execution must still respect permissions, account balances, fraud controls, and the rules of the payment system.
This is especially relevant to SaaS platforms. An AI assistant could help a business owner organize invoices, forecast cash needs, and prepare payment instructions. A more autonomous system might schedule approved payments within defined limits. But an agent should not be allowed to move funds merely because a language model inferred that doing so would be useful.
What this means for product teams: Separate AI planning from financial authorization and settlement. Use explicit user permissions, transaction limits, confirmation steps for sensitive actions, and auditable records of what the agent recommended and what the payment system actually executed.
Source: International Monetary Fund, How Agentic AI Will Reshape Payments, 2026
AI Use Cases Across the Embedded Finance Lifecycle
AI can support several stages of the customer journey, but each use case has different requirements for data, model validation, and human oversight.
| Lifecycle stage | AI capability | Important safeguard |
|---|---|---|
| Discovery | Identify when a financial feature may be relevant | Avoid manipulative or excessive targeting |
| Application | Extract information and help complete forms | Verify extracted data and obtain consent |
| Underwriting | Analyze cash flow and credit risk | Fairness testing and explainability |
| Transaction | Detect fraud and select payment routes | Real-time controls and fallback handling |
| Servicing | Forecast cash flow and predict payment issues | Monitor errors and provide user recourse |
| Operations | Reconcile transactions and summarize exceptions | Keep a verifiable financial record |
AI-Powered Embedded Lending for SaaS Platforms
Small businesses often have irregular revenue, seasonal demand, delayed invoices, and uneven expenses. A conventional credit application may not fully reflect these operating patterns, particularly for young businesses or firms with limited credit histories.
A SaaS platform may have useful information about how the business operates. Depending on the product and the permissions granted, it might observe sales, refunds, invoice aging, customer concentration, subscription revenue, inventory movement, or supplier payment timing. AI can turn these records into cash-flow forecasts and risk indicators that a lending partner can consider.
Merchant operating data
↓
Data permission and quality checks
↓
AI cash-flow analysis
↓
Risk and affordability assessment
↓
Lender’s underwriting decision
↓
Offer, disclosure, acceptance, and servicing
This workflow must preserve the lender’s responsibility for its credit decision where applicable. The SaaS platform may provide data, user experience, and analytical support, but the legal allocation of lending, servicing, disclosure, and compliance responsibilities depends on the product structure and jurisdiction.
AI in E-Commerce Checkout and Consumer Financing
E-commerce platforms can integrate installment plans, buy-now-pay-later products, credit offers, and payment options directly into checkout. AI can help detect fraud, estimate transaction risk, and improve the relevance of payment options.
However, there is an important boundary between helping customers understand payment choices and using behavioral signals to push them toward borrowing. A recommendation system should make the total cost, repayment schedule, eligibility conditions, and consequences of missed payments clear. It should not hide cheaper payment methods or create artificial urgency around credit.
For consumer financing, the lender’s eligibility and affordability rules should remain distinct from the retailer’s conversion goals. A retailer may benefit when more customers complete purchases, but that does not mean every customer should receive or accept a credit offer.
Useful AI applications include:
- Detecting account takeover and payment fraud
- Identifying suspicious patterns across devices and transactions
- Predicting payment failures where permitted data supports the task
- Improving checkout routing and reducing avoidable payment errors
- Supporting customer service with accurate financing information
- Detecting unusual refund and chargeback patterns
AI for Merchant Cash-Flow Forecasting
Cash-flow forecasting may be one of the most useful embedded-finance applications for SaaS platforms because it supports both financial decisions and day-to-day business operations.
A merchant may have strong sales but still face a short-term cash shortage because customer payments arrive after supplier invoices are due. A platform that only looks at revenue could miss this problem. A better forecast considers expected receipts, scheduled expenses, refunds, payroll, taxes, and the uncertainty around each estimate.
AI can help by identifying recurring patterns, estimating the likelihood of delayed payments, and detecting changes in business activity. Forecasts should include uncertainty rather than presenting one number as guaranteed.
Illustrative cash-flow intelligence dashboard
Customer receipts and scheduled payouts
Suppliers, payroll, rent, and subscriptions
Late invoices, sales volatility, and uncertainty
Review payment timing or available financing
The platform should present forecasts as decision support. It should not imply that a predicted shortfall makes borrowing the only solution. Other options may include changing payment timing, following up on invoices, reducing discretionary spending, or using existing cash reserves.
AI Integration Architecture
A production-grade embedded-finance system requires more than a model and a financial API. It needs a reliable integration layer that connects the non-financial platform with financial partners while protecting user data and preserving a clear record of every financial action.
E-commerce checkout, SaaS dashboard, marketplace, or business applicationEmbedded finance experience
Payments, lending application, account features, cards, or financial dashboard
Integration and orchestration layer
API gateway, identity checks, consent management, partner routing, webhooks, retries
AI and analytics layer
Fraud detection, cash-flow forecasting, risk signals, document processing, recommendations
Financial partners
Bank, lender, payment processor, card issuer, or regulated service provider
Control and monitoring layer
Access control, audit logs, reconciliation, model monitoring, incident handling
A robust design should keep financial execution separate from AI-generated recommendations. Models can generate scores, forecasts, summaries, and suggested actions, while deterministic services enforce permissions, transaction limits, and payment rules.
API Design, Data Quality, and Interoperability
Embedded finance depends on reliable exchange of data between systems. APIs connect the platform to financial partners, but the integration must handle incomplete records, duplicate events, delayed responses, expired credentials, and inconsistent data formats.
Important engineering requirements include:
- Explicit consent and clear data-use purposes
- Secure authentication and authorization
- Encryption in transit and at rest
- Idempotency controls to prevent duplicate financial actions
- Webhook verification and replay protection
- Reliable reconciliation between platform and partner records
- Versioned APIs and documented error handling
- Monitoring for latency, outages, and data-quality failures
- Clear ownership of customer support and incident response
AI adds its own data-quality requirements. A credit model trained on incomplete or inconsistent transaction records may generate unreliable assessments. A fraud model may mistake a platform migration or payment-provider change for suspicious behavior. Data lineage and operational monitoring are therefore part of the AI system, not separate administrative tasks.
Key Risks and Controls
| Risk | How it can appear | Control |
|---|---|---|
| Unfair credit decisions | Some customer groups receive systematically worse outcomes | Fairness testing, explanations, and review procedures |
| Data overreach | Platform data is reused beyond the user’s expectations or permission | Purpose limitation, consent, and data minimization |
| Fraud model errors | Legitimate customers are blocked or fraud is missed | Threshold testing, human review, and fallback routes |
| Partner dependency | A bank or processor outage interrupts the experience | Resilience planning and clear customer messaging |
| Model drift | Customer behavior or economic conditions change | Ongoing monitoring and controlled retraining |
| Autonomous payment error | An AI agent initiates an unintended payment | Explicit authorization, limits, confirmation, and audit logs |
Expert Recommendation
The recommended approach is to build embedded finance around a specific customer workflow, then introduce AI where it improves a measurable decision. A platform should not begin by collecting every possible data point or launching several financial products at once.
For an e-commerce platform, a sensible first stage may be payment fraud detection, checkout reliability, or clearer payment-choice experiences. For a SaaS platform serving small businesses, cash-flow forecasting, invoice analysis, and payment reconciliation may be more useful starting points than automated credit approval.
The product team should establish a clear division of responsibility between the platform, the financial partner, and the AI system. The platform may own the customer experience and data integrations, while a regulated partner may own lending or payment obligations. The precise responsibilities must be documented for the product and jurisdiction.
A practical strategy is to:
- Identify one high-value customer problem before selecting the AI model
- Map the data required and confirm that its use is permitted
- Establish a reliable financial-partner integration before automating decisions
- Begin with decision support and controlled automation
- Measure customer outcomes alongside conversion and revenue
- Test for fairness, privacy, security, and model drift
- Keep financial authorization and settlement under explicit controls
- Expand only after the initial use case demonstrates reliable performance
Expert Perspective on AI and Payment Infrastructure
The International Monetary Fund’s 2026 analysis highlights a central design challenge: “the probabilistic nature of AI” must coexist with the deterministic requirements of payment infrastructure. The note examines how AI agents may help initiate and coordinate payments while raising questions about traceability, opacity, cybersecurity, systemic effects, and legal accountability.
This is a useful principle for embedded-finance builders. AI may be suitable for interpreting a request, forecasting a cash shortfall, identifying a suspicious payment, or recommending a payment schedule. The actual movement of money should remain governed by explicit authorization, validated instructions, transaction controls, and reliable settlement systems.
Source: IMF, How Agentic AI Will Reshape Payments, 2026
Implementation Roadmap
Discovery and Product Design
Identify the user problem and the financial service that can solve it. Map the journey from the first relevant moment in the platform through application, eligibility, acceptance, transaction execution, servicing, and support.
Data and Partner Readiness
Confirm which data is available, who controls it, what consent is required, and which financial partner will provide the underlying product. Define the responsibilities for underwriting, disclosures, fraud monitoring, complaints, and regulatory reporting.
Build the Integration Foundation
Implement secure APIs, authentication, consent management, idempotency, webhooks, reconciliation, error handling, and monitoring. Test failure scenarios such as partner outages, delayed responses, duplicate messages, and expired credentials.
Develop and Validate the AI Capability
Train or configure the model using data appropriate to the intended use. Evaluate it on representative samples, compare it with a simpler baseline, and test performance across relevant customer groups and operating conditions.
Run a Controlled Pilot
Start with a limited customer segment or a decision-support workflow. Track model quality, operational reliability, customer experience, and financial outcomes before expanding access.
Monitor and Improve
Review model drift, complaints, failed transactions, unexpected outcomes, security incidents, and partner performance. Update models through controlled processes and retain records of significant changes.
KPIs for AI-Enabled Embedded Finance
| KPI | What it measures | Why it matters |
|---|---|---|
| Payment success rate | Share of attempted payments completed successfully | Measures payment reliability |
| Fraud loss rate | Confirmed fraud losses relative to transaction volume | Measures financial risk |
| False-decline rate | Legitimate transactions incorrectly declined | Measures avoidable customer friction |
| Credit performance | Delinquency, default, and repayment outcomes | Measures lending quality |
| Forecast accuracy | Difference between predicted and actual cash flow | Measures usefulness of cash insights |
| Customer complaints | Complaints about payment, credit, or automated decisions | Measures trust and customer harm |
| API reliability | Availability, latency, and error rates | Measures integration quality |
Future Predictions: 2027–2030
2027: Contextual Finance Becomes More Common
More platforms will connect financial products to specific moments in the customer journey. E-commerce platforms may improve payment choice and fraud controls, while SaaS platforms may connect invoicing, payment acceptance, and cash-flow insights. The competitive advantage will depend on whether these features solve real user problems without adding unnecessary friction.
2028: Cash-Flow Intelligence Expands in Vertical SaaS
Platforms serving particular industries will have more opportunities to build financial insights around their specialized workflows. A construction platform, for example, may understand project milestones and invoice timing, while a retail platform may have insight into inventory cycles and seasonal sales. AI can help translate these operational signals into forecasts that support business planning and lender assessment.
2029: Financial Workflows Become More Automated
AI assistants may increasingly help users reconcile transactions, organize invoices, identify upcoming obligations, prepare payment instructions, and compare financing options. Some actions may be automated within defined limits, but consequential financial decisions will require strong authorization and accountability controls.
2030: Embedded Finance Moves Toward Coordinated Financial Operations
The next stage may connect payments, credit, cash forecasting, reconciliation, and financial administration into a more coordinated experience. Rather than opening separate tools for each task, a business may use one platform to understand its position and manage approved actions. The pace of adoption will depend on interoperability, regulation, trust, and the reliability of AI systems.
These are forward-looking scenarios, not guaranteed outcomes. Their realization will depend on financial-partner readiness, data access, customer demand, and the ability to demonstrate safe and measurable value.
Startup Opportunities
AI-enabled embedded finance creates opportunities for software companies, fintech infrastructure providers, and vertical SaaS businesses. The strongest opportunities are often focused products that solve a specific problem rather than broad platforms attempting to provide every financial service.
- AI cash-flow intelligence for SaaS: Forecast receipts, expenses, and short-term funding needs for small businesses
- Embedded lending decision support: Prepare cash-flow summaries and application data for a lending partner
- AI payment orchestration: Help platforms select payment routes while respecting cost, reliability, and compliance constraints
- Graph-based payment fraud detection: Identify relationships among suspicious transactions, devices, accounts, and merchants
- AI reconciliation assistant: Match payments, invoices, refunds, and accounting records while flagging exceptions
- Embedded finance API monitoring: Detect integration failures, unusual partner behavior, and reconciliation gaps
- AI financial operations copilot: Help business users understand balances, upcoming obligations, and approved payment actions
- Industry-specific financing intelligence: Build underwriting support around the operating patterns of a particular sector
A defensible product will need more than a strong model. It will need reliable integrations, trustworthy data, clear responsibilities, a useful customer experience, and measurable improvements over the existing process.
Frequently Asked Questions
What is AI in embedded finance?
It is the use of AI to improve financial services delivered inside non-financial products, such as e-commerce stores, SaaS platforms, and marketplaces. Common applications include fraud detection, cash-flow forecasting, credit assessment, payment optimization, and financial workflow automation.
How can e-commerce platforms use AI in embedded finance?
They can use AI to identify suspicious transactions, reduce payment friction, improve payment routing, support checkout financing workflows, and help customers understand available payment options. Credit eligibility and lending decisions should follow the applicable lender and regulatory requirements.
How can SaaS companies use AI for embedded lending?
With appropriate permissions, SaaS platforms can analyze operational data such as invoices, sales, payment timing, and recurring expenses. These insights may help a lending partner assess cash flow, but they should be validated and combined with other relevant information.
Does AI replace banks or financial institutions?
No. AI can support analysis, customer experience, and operational processes, but it does not remove the need for the financial institutions, payment providers, or regulated entities responsible for the underlying services.
What is the biggest risk of AI-enabled embedded finance?
Key risks include unfair credit decisions, inappropriate use of customer data, fraud-model errors, poor integration reliability, and automated financial actions without adequate authorization. These risks require technical controls and clear governance.
Should a platform build its own AI credit model?
Not necessarily. A platform should first define the use case, data rights, partner responsibilities, and validation requirements. Depending on its capabilities and regulatory role, it may be more appropriate to provide analytics to a lending partner or use a validated third-party solution.
Final Perspective
AI can make embedded finance more useful when it connects financial services to the real work customers are already doing. E-commerce platforms can improve payment experiences and fraud controls, while SaaS platforms can use operational context to support cash-flow planning, payment reconciliation, and access to business finance.
The research points to several important conclusions. A 2026 review of 118 digital-lending studies shows the promise of AI credit assessment alongside continuing gaps in fairness, explainability, real-time adaptation, and governance. A 2026 study of interoperable payment data finds that payment histories can complement credit-bureau information, while also showing that data-based screening can disadvantage borrowers with limited records.
A 2026 IEEE study demonstrates how graph-derived features can add useful information to e-commerce fraud detection, although the gains over conventional models were not transformative. The IMF’s 2026 analysis further highlights why autonomous payment capabilities need clear authorization, traceability, and deterministic controls.
Together, these findings suggest that successful embedded finance is not simply a matter of placing a financial API inside an app. It requires a carefully designed relationship between the platform’s data, the user’s needs, the financial partner’s responsibilities, and the AI system’s role.
The most useful approach is to start with a specific problem, build a reliable integration, use AI where it adds measurable value, and preserve clear controls over sensitive decisions and the movement of money.
Research Sources
- A Comprehensive Literature Review on AI-Based Credit Assessment in Digital Lending, Expert Systems with Applications, 2026
- Beyond the Bureau: Interoperable Payment Data for Loan Screening and Monitoring, Journal of Financial Intermediation, 2026
- E-Commerce Transaction Fraud Detection Using GNN-Based Feature Embedding and Machine Learning Methods, IEEE Access, 2026
- Safeguarding FinTech Innovations with Machine Learning: Comparative Assessment of Various Approaches, Research in International Business and Finance, 2023
- Boston Consulting Group, Moving Embedded Finance from Promise to Practice, 2025
- International Monetary Fund, How Agentic AI Will Reshape Payments, 2026
- Harvard Kennedy School, Fintech Reimagined: Exploring the Value of Embedded Finance for Small and Medium Businesses
- CGAP, Solutions to Protect Consumers from Fraud in Digital Finance, 2026

Leave a Reply