
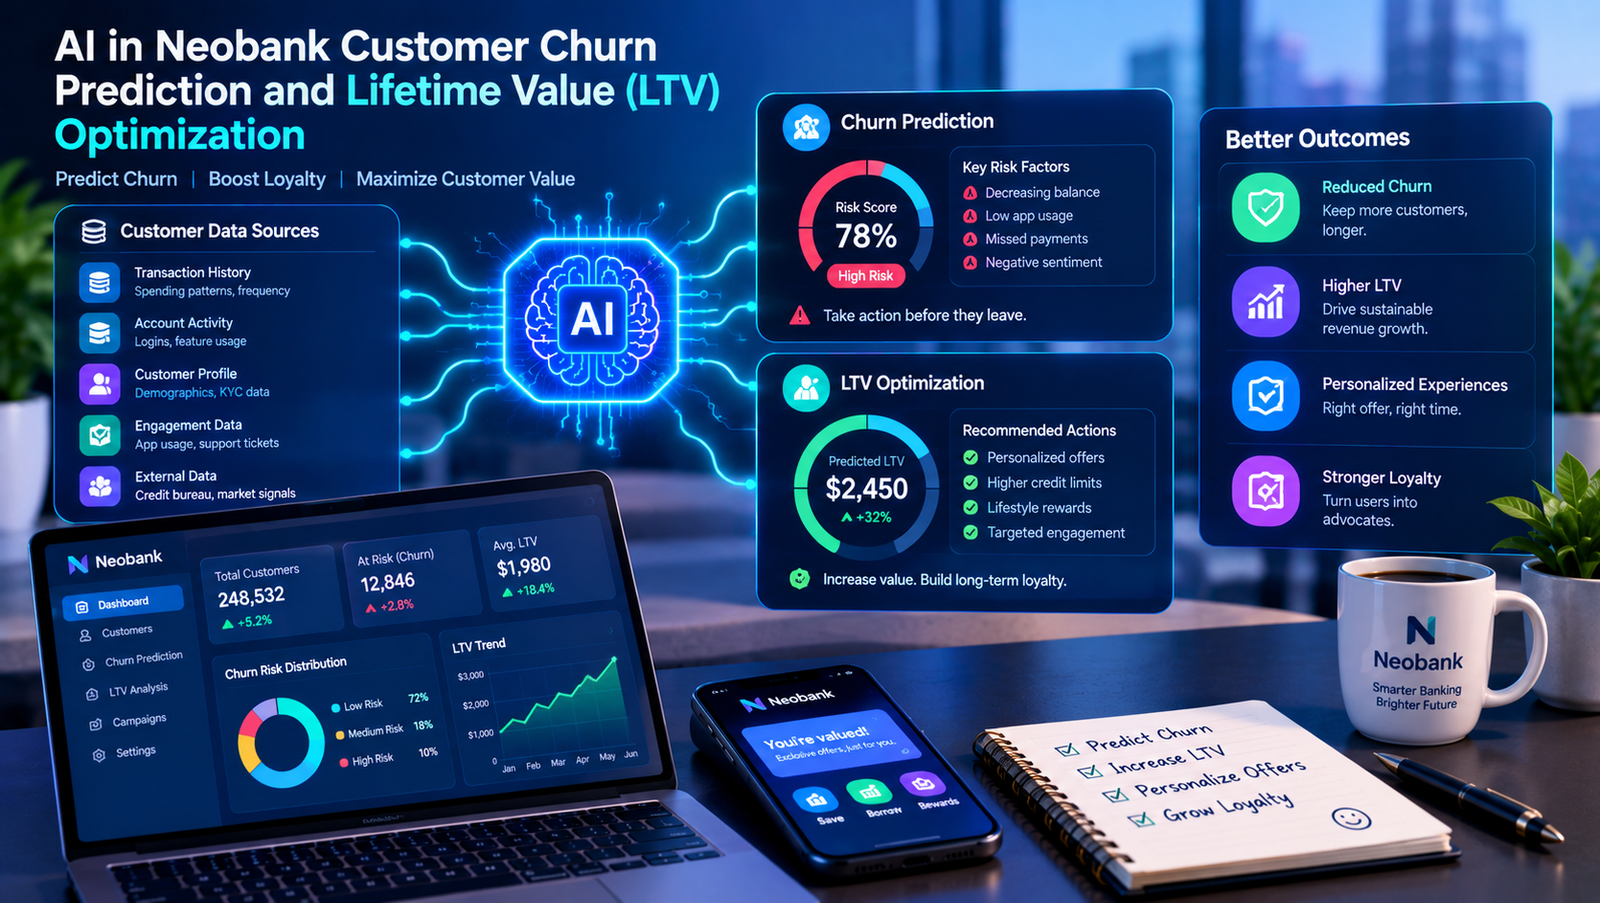
Primary topic: Artificial intelligence in digital banking customer retention and lifetime value optimization
Research focus: Predictive churn modeling, early disengagement detection, customer lifetime value, deposit outflow prediction, product adoption, personalized retention, explainable AI, customer profitability, and responsible customer engagement
Why Churn and Lifetime Value Need to Be Managed Together
Neobanks operate in a digital environment where customers can open accounts, compare providers, move money, and stop using a service with relatively little friction. A customer may keep an account open while shifting most of their financial activity to another bank. As a result, account closure alone is a weak measure of customer loss.
For a neobank, customer churn can take several forms. A user might close an account completely, stop using a debit card, move recurring payments elsewhere, stop depositing income, or retain only a small balance. These behaviors have different commercial implications. A customer who stops using a card but maintains a salary account may still have substantial future value, while a customer who moves deposits and recurring activity away may be approaching a deeper relationship breakdown.
Customer lifetime value (LTV), also called customer lifetime value or CLV, estimates the economic contribution a customer is expected to generate over a defined future period. In banking, this can include net interest income, interchange revenue, subscription fees, lending contribution, and other product-related income, after accounting for relevant costs and risk.
AI connects these two questions:
- Churn prediction: Which customers are likely to reduce or end their relationship?
- LTV estimation: What future economic contribution could each customer generate?
- Retention optimization: Which intervention is likely to preserve profitable, sustainable relationships?
- Incrementality measurement: Did the intervention actually change customer behavior, or would the customer have stayed anyway?
The connection matters because a high churn probability does not automatically mean a customer deserves an expensive retention offer. The customer may have low expected future contribution, or the reason for leaving may be something a discount cannot fix. Conversely, a customer with moderate churn risk may have a high-value relationship that justifies timely service recovery.
How AI Changes the Neobank Retention Model
Traditional churn models often classify customers into two groups: likely to leave and likely to stay. More advanced systems estimate the probability of churn over a particular period, identify the behaviors associated with that risk, and estimate the likely financial consequences.
For neobanks, the next step is to model the customer relationship as a changing sequence of financial behaviors. Transaction activity, salary deposits, recurring bills, savings balances, card usage, support interactions, product adoption, and app engagement can all provide signals. The system should interpret them in context rather than treating every decline in activity as a warning.
Visual: From Customer Activity to Retention Decision
Transactions, balances, app activity
Churn risk and timing
Expected future contribution
Service, product, or no offer
This architecture helps a neobank move from reactive campaigns to a more precise retention process. It also creates a way to distinguish between customers who need help, customers who need a better product experience, and customers whose behavior does not justify intervention.
Research Study: Trust, Security, and Nonlinear Retention in Neobanking
A 2026 study published in FinTech examined customer retention intention in neobanking using an explainable machine-learning framework. The researchers analyzed survey responses from 305 neobank users and compared regularized linear models, a theory-informed benchmark, and XGBoost. They used repeated nested cross-validation and tools including SHAP to investigate which factors contributed to the predictions.
The study found that XGBoost outperformed the linear benchmarks on the reported out-of-sample prediction measures. Trust-related indicators contributed the largest share of predictive importance, followed by perceived security and switching costs. The analysis also suggested that these relationships were not necessarily linear. For example, the relationship between trust and retention may vary across customer groups or levels of perceived security.
This is directly relevant to neobanks because a customer’s decision to stay is not determined only by transaction volume or account balance. Confidence in the provider, the perceived safety of funds, and the experience of resolving problems can influence whether the customer continues using the service.
However, this study measured retention intention, not verified future account closure or realized customer lifetime value. Its sample of 305 users also limits how confidently its findings can be generalized to every market or neobank. It is useful evidence for feature design and hypothesis development, but it does not establish that the same model will predict actual churn in a production banking environment.
Implication for product teams: Include trust, security experience, and service-recovery signals in the retention research program. Test whether they improve predictions of observed behavior, rather than assuming survey-based retention intention is equivalent to real-world retention.
Research Study: AI-Enabled Neobanking, Service Quality, and Customer Loyalty
A 2025 study in the International Journal of Quality & Reliability Management investigated what attracts or discourages customers from using AI-enabled neobanking services. The researchers collected survey data from 439 consumers in India and used partial least squares structural equation modeling to examine relationships among service quality, online brand experience, trust, and customer loyalty.
The study reported that personalization, responsiveness, and website design significantly influenced perceived service quality. Service quality was associated with online brand experience, customer trust, and customer loyalty. Trust and brand experience also contributed to customer loyalty in the model.
This research adds an important dimension to churn prediction. A neobank should not treat customer behavior as an isolated data problem. The product experience itself can create or reduce the conditions that lead to disengagement. If an app is difficult to use, support is slow, or personalization feels irrelevant, a churn model may identify risk without addressing its cause.
The study is based on cross-sectional survey data, so it establishes relationships within the research model rather than proving that a particular product change will reduce actual churn. Its India-based sample also means the findings should be validated in other markets.
Implication for neobanks: Connect churn analytics with product analytics and customer-experience research. If users with repeated support failures show elevated churn risk, test whether faster resolution reduces subsequent inactivity and account attrition.
Source: What Attracts Me or Prevents Me from Using AI-Enabled Neo-Banking Services? 2025
Research Study: Machine Learning for Banking Customer Churn
A 2025 study in Discover Sustainability examined an ensemble-based approach to predicting customer churn in banking. It combined demographic, financial, and behavioral variables, including account balance, tenure, credit score, and activity levels. The researchers evaluated a voting-classifier approach intended to improve churn classification.
The relevance to neobanks lies in the combination of customer attributes and observed behavior. A digital bank can often collect frequent activity signals, but those signals become more useful when interpreted alongside relationship duration, product ownership, balance patterns, and other relevant account information.
An ensemble model can combine the strengths of several classifiers, but the use of an ensemble does not automatically guarantee better business results. Performance depends on the quality of the data, the definition of churn, the evaluation design, and whether the model generalizes to future customers.
A further concern is class imbalance. In many banking datasets, most customers do not churn during the observation period. A model can achieve high accuracy by predicting that nearly everyone will stay, while missing the customers the retention team needs to identify. Precision, recall, calibration, and the cost of different errors are therefore more informative than accuracy alone.
Implication for neobanks: Evaluate models against a clearly defined business event, such as a sustained reduction in primary-account activity or verified account closure. Use time-based validation and report the number of customers identified, the proportion who actually churn, and the value of the resulting interventions.
Source: Ensemble-Based Customer Churn Prediction in Banking, 2025
Research Study: Customer Lifetime Value Modeling in Retail Banking
A 2023 research paper, Modelling Customer Lifetime-Value in the Retail Banking Industry, presented a machine-learning framework for estimating customer lifetime value over flexible time horizons. The approach used product-level propensity models and was designed for long-lasting customer relationships.
The authors reported a 43% improvement in out-of-time CLV prediction error relative to a baseline approach in their testing. They also reported that customers ranked in the top 10% by propensity to take up investment products were 3.2 times more likely than a randomly selected customer to take up an investment product in the following year.
These results illustrate why lifetime value should not be reduced to a static customer segment. A customer’s future contribution can depend on which products they may adopt, how long they remain active, and how their relationship develops. For a neobank, this could mean estimating future contribution from a salary account, savings product, card, subscription tier, or eligible lending product.
The study concerns retail banking rather than neobanks specifically, and its reported results should not be assumed to transfer unchanged to a different institution. Still, it provides a relevant modeling framework for combining future relationship duration with product-level behavior.
Implication for neobanks: Estimate value over explicit horizons, such as 12, 24, or 36 months. Separate expected revenue from contribution after servicing, rewards, funding, credit losses, and other relevant costs. Use product propensity as a forecast, not as a reason to push unsuitable products.
Source: Modelling Customer Lifetime-Value in the Retail Banking Industry, 2023
Research Study: Open Banking Data and Potential Customer Lifetime Value
A 2025 study, Potential Customer Lifetime Value in Financial Institutions: The Usage of Open Banking Data to Improve CLV Estimation, explored how open banking data could broaden the measurement of customer value. Traditional CLV models often use information held by one institution. That view can miss financial activity occurring elsewhere.
The researchers proposed a Potential Customer Lifetime Value framework that uses open banking data to estimate retention probability and potential contribution margins associated with activity across competing institutions. The paper reported a potential CLV estimate 21.06% above actual CLV in its analysis.
This does not mean that a bank can automatically capture 21.06% more revenue. The figure represents the study’s estimated potential relative to its actual-CLV measure, not a demonstrated uplift from a retention campaign. Its practical value is that consented external financial data may reveal a broader picture of a customer’s financial relationship.
For a neobank, open banking data could help distinguish between a customer who has little financial activity and a customer who is active but uses another provider for salary, savings, or recurring payments. That distinction can improve both churn diagnosis and the estimate of potential product relevance.
Implication for neobanks: Where lawful and consented, use external account data to understand customer needs and financial fragmentation. Apply data minimization, clear consent, purpose limitation, and controls that prevent sensitive information from being used in ways customers would not reasonably expect.
Research Study: Predicting Financial Fragmentation Before Full Churn
An August 2026 preprint, Beyond Churn: Predicting Financial Fragmentation in Retail Banking with Temporal Machine Learning, focuses on an important stage before a customer fully leaves. The authors define financial fragmentation as the movement of deposits, investments, and recurring financial activity to external institutions while the customer may still retain the original account.
The research uses 595,220 client-month observations and 346 engineered features. Its four-stage XGBoost framework estimates whether an external outflow will occur within 90 days, the expected amount, the originating product, and the destination institution. The authors report a test precision-recall AUC of 0.823 for the primary classifier.
This is a useful extension of conventional churn modeling because a binary churn label can arrive too late. A customer may have already moved a substantial share of their financial relationship before closing an account. Detecting this shift can give a neobank more time to investigate whether the cause is a product limitation, a temporary financial need, or a competitor offering a better fit.
The paper is a preprint and should be treated as preliminary evidence until peer review and further validation. It also concerns retail banking, not exclusively neobanks. Its results are best understood as evidence for a promising modeling direction rather than a guaranteed performance benchmark.
Implication for neobanks: Track changes in primary-account behavior and financial flows, not just account closure. Build separate predictions for reduced engagement, deposit outflow, product abandonment, and full churn.
What These Studies Mean for Neobank Strategy
The research points toward a more complete model of customer relationships. Churn prediction identifies risk, but the reason for that risk and the economic value of the relationship determine what the business should do next.
| Research direction | Evidence contribution | Neobank application |
|---|---|---|
| Explainable neobank retention | Trust and security can be important, nonlinear predictors | Include trust and service signals in retention analysis |
| AI-enabled service quality | Personalization and responsiveness relate to loyalty | Connect product experience with churn risk |
| Ensemble churn modeling | Multiple models can support churn classification | Compare models using time-based tests and cost-sensitive metrics |
| Banking CLV prediction | Future value can be modeled across products and time horizons | Estimate contribution, not just revenue or balance |
| Open banking CLV | Consented external data can reveal broader financial relationships | Identify unmet needs and financial fragmentation |
| Temporal fragmentation prediction | Outflows may be detectable before full account closure | Intervene before the relationship is lost |
Designing a Neobank Churn Prediction Model
The first modeling decision is the definition of churn. For a neobank, a single definition is rarely sufficient. An account can remain legally open while the customer stops using it as their primary financial account.
A useful model portfolio can predict several outcomes separately:
- Account closure within a defined period
- Sustained decline in card or payment activity
- Salary or regular income deposits moving elsewhere
- Significant reduction in deposits or savings balances
- Cancellation of a paid subscription
- Loss of recurring payment activity
- Reduced product engagement
- Movement of financial activity to another provider, where observable and lawfully available
The observation window and prediction horizon must be explicit. For example, a model could use the previous 90 days of behavior to predict a defined churn event over the next 30 or 90 days. This helps the retention team act before the outcome occurs and makes model performance easier to evaluate.
Features That Matter in Digital Banking
A neobank can construct features from several data groups, subject to applicable privacy rules and the customer’s permissions.
Account behavior
- Transaction frequency
- Active days
- Balance changes
- Income deposit consistency
Product relationship
- Products used
- Card activity
- Recurring payments
- Savings engagement
Experience signals
- Support contacts
- Complaint resolution
- App errors
- Failed payments
Relationship history
- Tenure
- Previous inactivity
- Product adoption
- Prior retention response
Feature design must avoid data leakage. If the model uses information recorded after a customer has already decided to leave, it may appear highly accurate without providing a useful early warning. Time-based validation is particularly important because customer behavior and product offerings change over time.
Customer Lifetime Value: From Revenue to Contribution
A useful LTV model should estimate the future contribution of a customer rather than simply multiplying current monthly revenue by an assumed number of months.
A simplified structure is:
Expected LTV
Expected future contribution from products and services
minus
Expected servicing, rewards, funding, and acquisition costs
minus
Expected credit losses and other relevant risk costs
adjusted for
Retention probability, timing, and discount rate
The exact components depend on the neobank’s business model. A card-led neobank may derive contribution from interchange and subscriptions, while a savings-focused provider may place greater weight on net interest margin and funding costs. A lender must account for expected credit losses, capital, and risk-adjusted lending returns.
A model should also separate observed value from potential value. A customer with limited current activity may have future potential, but that potential should not be treated as guaranteed revenue. Product propensity models can estimate the likelihood of future adoption, while controlled experiments determine whether a particular offer actually increases adoption.
Visual: Combining Churn Risk and Customer Value
A churn score alone is not a retention strategy. Combining risk and value creates a more useful decision framework.
| Customer group | Likely response | Potential action |
|---|---|---|
| High value, high risk | Potentially material relationship loss | Investigate cause, resolve service issues, offer relevant help |
| High value, low risk | Relationship appears stable | Protect service quality and support suitable needs |
| Low value, high risk | Retention may be costly relative to contribution | Use low-cost service improvements or no offer |
| Low value, low risk | Limited immediate retention concern | Provide a good standard experience without unnecessary targeting |
This framework is a decision aid, not a reason to provide worse service to customers with lower predicted value. Core banking access, security, complaint handling, and fair treatment should not depend on commercial LTV scores.
Why Predictive Churn Is Not the Same as Preventable Churn
One of the most important mistakes in retention analytics is assuming that a customer who is likely to leave can necessarily be persuaded to stay.
A churn model estimates the probability of an event. It does not automatically estimate whether a particular intervention will change that event. A customer may be leaving because of relocation, financial hardship, a product mismatch, dissatisfaction, or a better offer elsewhere. Different causes require different responses.
Neobanks should therefore distinguish between three predictions:
- Churn propensity: How likely is the customer to leave?
- Treatment effect: How much could a specific intervention change that probability?
- Economic value: Is the expected benefit of that change greater than the intervention cost?
This is where uplift modeling and controlled experimentation become valuable. Instead of targeting customers simply because they have a high risk score, the bank estimates which customers are more likely to respond to a specific action.
For example, a fee reminder or a simpler account setting may help one customer, while another may need a failed-payment issue resolved. A cash incentive could be unnecessary for both. The best intervention depends on the cause of risk and the likely response.
AI-Powered Retention Interventions for Neobanks
Service Recovery and Friction Reduction
When a customer experiences repeated failed payments, card declines, app errors, or unresolved support cases, the most appropriate retention action may be to fix the problem. AI can identify patterns across support tickets, transaction failures, and product events, then route cases to the team best placed to resolve them.
A service-recovery system should prioritize severity and customer impact, not only LTV. A high-value customer may justify proactive outreach, but essential service issues should be resolved fairly for all affected users.
Personalized Product Recommendations
AI can estimate which products may fit a customer’s observed needs, such as savings tools, spending controls, or a relevant account tier. These recommendations should be based on suitability and customer benefit, not solely on predicted revenue.
A product recommendation can also be a retention intervention when it solves a genuine problem. For example, a customer who frequently uses budgeting features may value better spending insights more than a cash reward.
Subscription and Fee Optimization
For neobanks with paid tiers, churn risk may increase when customers do not use the features included in their subscription. AI can identify unused benefits and explain them in context, or help customers move to a tier that better fits their needs.
The objective should be to improve fit and transparency. Making cancellation difficult or using confusing prompts may temporarily reduce observed cancellations but damage trust and increase complaints.
Financial Wellbeing and Cash-Flow Support
Where the product includes budgeting or cash-flow tools, AI can identify recurring financial stress signals and offer relevant support. Such systems need careful controls because financial activity can reveal sensitive information. They should avoid presenting speculative inferences as facts or using vulnerability to push credit products.
Architecture for an AI-Powered Neobank Retention Platform
Transactions, balances, product usage, service interactions, consented external data
Activity trends, payment reliability, product relationships, relationship history
Churn probability, outflow risk, future contribution, product propensity
Intervention selection, eligibility, contact limits, expected incremental value
Consent, privacy, fairness, explainability, audit logs, model monitoring
Holdout groups, retention uplift, net contribution, complaints, customer outcomes
The platform should support scheduled scoring and event-triggered scoring. A monthly model may be adequate for long-term relationship planning, while a failed salary deposit or a sudden change in account activity may require a faster review. Not every signal needs an immediate marketing message; some should trigger internal investigation or a service-quality check.
Model Evaluation: Metrics That Matter
A model should be evaluated using both statistical and business measures. Accuracy alone can be misleading when churn is relatively uncommon.
| Metric | What it tells the team | Why it matters |
|---|---|---|
| Precision | Share of flagged customers who churn | Helps manage wasted outreach |
| Recall | Share of churners identified | Shows how much churn the model captures |
| PR-AUC | Precision-recall trade-off | Useful with imbalanced churn labels |
| Calibration | Whether predicted probabilities match observed rates | Supports decisions based on risk thresholds |
| Incremental retention | Additional customers retained because of an intervention | Separates impact from correlation |
| Net incremental contribution | Incremental value after intervention costs | Connects model performance to economics |
| Complaint and opt-out rates | Customer response to interventions | Helps detect harmful or excessive targeting |
Responsible AI, Privacy, and Fair Treatment
Neobank data can reveal income patterns, spending habits, financial stress, and other sensitive aspects of a customer’s life. Using these data for retention requires clear purpose limitation, access controls, security, and compliance with applicable privacy and financial-services requirements.
Important safeguards include:
- Collect only the data needed for a defined purpose
- Respect consent and applicable data-sharing permissions
- Restrict access to sensitive financial features
- Test model performance across relevant customer groups
- Avoid using protected or sensitive attributes in ways that create unfair treatment
- Explain consequential decisions in language customers and staff can understand
- Keep audit trails for model outputs and retention actions
- Monitor whether offers, fees, or service quality differ unfairly across groups
- Provide a way to correct inaccurate customer information
- Reassess models when products, markets, or customer behavior change
A churn score should not be used to deny a customer essential support or to make opaque decisions about access to basic banking services. Retention optimization should improve the relationship, not exploit a customer’s financial vulnerability.
Expert Recommendation
The recommended approach is to build a customer relationship intelligence system, not just a churn classifier. Start with a clear definition of churn and a reliable customer-level timeline. Then build separate models for churn probability, financial fragmentation, and future contribution. Keep these outputs distinct so that a high-risk score is not mistaken for high value or high responsiveness to an offer.
Use interpretable models as baselines and compare them with gradient-boosted trees or other suitable methods. For sequential behavior, test temporal models only when the data volume and validation design justify their added complexity. Evaluate all models on later time periods and monitor calibration as customer behavior changes.
Most importantly, measure retention campaigns with randomized holdout groups or another credible causal design. If customers receiving an offer are more likely to stay, that result may reflect the model’s ability to select already-loyal customers rather than the offer’s actual effect. Incrementality is the difference between what happened with the intervention and what would likely have happened without it.
Expert perspective — editorial synthesis: “Predict the risk, understand the reason, estimate the value, and test whether the action truly changes the outcome.”
This principle captures the difference between a model that produces a churn score and a system that creates measurable customer and business value.
Implementation Roadmap
Build the measurement foundation
Define churn events, observation windows, prediction horizons, and the financial meaning of a retained customer. Audit whether the available data can distinguish account closure from reduced primary-account usage.
Develop a reliable baseline
Start with a transparent baseline such as logistic regression, then compare it with tree-based models. Use time-based splits, preserve realistic churn prevalence in the test set, and check for leakage.
Add customer value estimation
Estimate future contribution over a defined horizon. Include product-level contribution, expected costs, risk, and retention probability. Validate forecasts against realized outcomes as they become available.
Connect predictions to interventions
Map common churn signals to relevant actions. Service failures should lead to service recovery; low product engagement may call for education or better product fit. Avoid defaulting to discounts.
Run controlled experiments
Use holdout groups to measure incremental retention, incremental contribution, customer satisfaction, complaints, and opt-outs. Do not judge success only by campaign conversion.
Monitor and improve
Review model calibration, data quality, performance by customer group, and intervention outcomes. Retrain or revise the system when behavior or product conditions change.
Future Predictions: 2027–2030
2027: Churn Models Move Toward Earlier Behavioral Signals
Neobanks are likely to place more emphasis on leading indicators such as declining primary-account activity, recurring payment changes, and reduced deposit engagement. Account closure will remain an important outcome, but it will increasingly be treated as one stage in a broader disengagement process.
2028: Churn and LTV Models Become More Closely Connected
Customer-level decision systems will increasingly combine churn probability, future contribution, and expected response to an intervention. This should help teams distinguish customers who need service recovery from those who may benefit from a suitable product or pricing change.
2029: Open Banking Expands Relationship-Level Analytics
Where customer permission and regulation allow, external account data may help neobanks identify financial fragmentation and understand which needs are not being met. The competitive advantage will depend on consent, data quality, and whether insights lead to useful customer outcomes.
2030: Retention Decisions Become More Adaptive
AI systems may increasingly select among service recovery, product guidance, pricing options, and no intervention based on observed outcomes. More advanced systems may estimate treatment effects at the customer level, but institutions will still need controlled testing, human oversight, and clear restrictions on sensitive-data use.
These are directional forecasts based on current research trends, not guaranteed outcomes. Adoption will depend on data access, model reliability, regulation, customer trust, and the economics of digital banking.
Key KPIs for Neobank Churn and LTV Optimization
| KPI | Purpose |
|---|---|
| Churn rate by cohort | Track retention across acquisition periods and customer groups |
| Primary-account retention | Measure whether customers continue using the neobank as a main account |
| LTV forecast error | Compare predicted contribution with realized contribution |
| Retention uplift | Measure the additional retention caused by an intervention |
| Net incremental contribution | Measure financial benefit after rewards and campaign costs |
| Time to detect disengagement | Measure how early the system identifies weakening relationships |
| Customer complaint rate | Check whether interventions create friction or harm |
Frequently Asked Questions
What is AI-powered customer churn prediction in neobanking?
AI-powered churn prediction uses customer behavior, account activity, product usage, and other permitted data to estimate the likelihood that a customer will reduce or end their relationship with a neobank. It can identify warning signs before account closure occurs.
How does customer lifetime value help reduce neobank churn?
LTV estimates the future economic contribution of a customer. When combined with churn risk, it helps a neobank evaluate which retention actions may be financially worthwhile. It should not determine access to essential services or fair treatment.
Which data can AI use to predict neobank churn?
Depending on consent and applicable law, models may use transaction frequency, balance trends, income deposits, card activity, product usage, customer tenure, support interactions, failed payments, and app engagement. External open banking data may provide additional insight when customers have granted appropriate permission.
Which AI models are used for banking churn prediction?
Common approaches include logistic regression, random forests, gradient-boosted trees such as XGBoost, ensemble classifiers, and temporal models. Model choice should depend on the data, the prediction horizon, interpretability needs, and performance on future-period tests.
Can AI predict when a neobank customer will leave?
AI can estimate the probability of churn within a defined time window, such as the next 30 or 90 days. Predicting the exact date is more difficult and depends on the quality of behavioral data and the stability of customer patterns.
What is the difference between churn prediction and retention uplift modeling?
Churn prediction estimates who is likely to leave. Uplift modeling estimates whose behavior may change because of a particular intervention. The second question is important because a high-risk customer may not respond to a discount or marketing message.
How can neobanks measure whether AI improves retention?
They should compare intervention and control groups, measure incremental retention, calculate net contribution after intervention costs, and monitor customer experience. A higher retention rate among targeted customers alone does not prove that the AI campaign caused the improvement.
Final Perspective
AI can help neobanks understand customer relationships before those relationships disappear. The most useful systems will not rely on account closure as the only definition of churn. They will monitor changes in financial activity, product engagement, service experience, and the movement of deposits or recurring payments.
The research supports several distinct building blocks. A 2026 neobank study highlights trust, security, and nonlinear retention patterns. A 2025 study of AI-enabled neobanking connects service quality with trust and loyalty. Banking churn research demonstrates the value of machine-learning classification, while customer lifetime value research shows how future contribution and product propensity can be modeled over time. Open banking research expands the view beyond a single institution, and recent temporal modeling explores the earlier stage of financial fragmentation.
These findings should not be treated as proof that a single model will work for every neobank. Survey-based retention intention, benchmark churn datasets, retail banking CLV, and preprint research each have different limitations. Production systems need institution-specific validation and ongoing measurement.
The practical direction is clear: combine churn risk, customer value, intervention effectiveness, and customer outcomes. Use AI to identify what may be happening, investigate why it is happening, and select a proportionate response. Then test whether that response actually improves the relationship.
A neobank that follows this approach can move beyond reactive retention campaigns toward a more measurable, explainable, and customer-centered strategy.
Research Sources
- Trust, Security, and Nonlinear Retention Dynamics in FinTech Neobanking: An Explainable Machine Learning Approach, 2026
- What Attracts Me or Prevents Me from Using AI-Enabled Neo-Banking Services? Unveiling the Nexus Between Service Quality and Customer Loyalty, 2025
- Ensemble-Based Customer Churn Prediction in Banking: A Voting Classifier Approach, 2025
- Modelling Customer Lifetime-Value in the Retail Banking Industry, 2023
- Potential Customer Lifetime Value in Financial Institutions: The Usage of Open Banking Data to Improve CLV Estimation, 2025
- Beyond Churn: Predicting Financial Fragmentation in Retail Banking with Temporal Machine Learning, 2026 preprint
- The Customer Churn Prediction with Artificial Intelligence Approaches in Banking Sector, 2026
- Investigating Customer Churn in Banking: A Machine Learning Approach and Visualization App, 2024
- Propension to Customer Churn in a Financial Institution: A Machine Learning Approach, 2022

Leave a Reply