
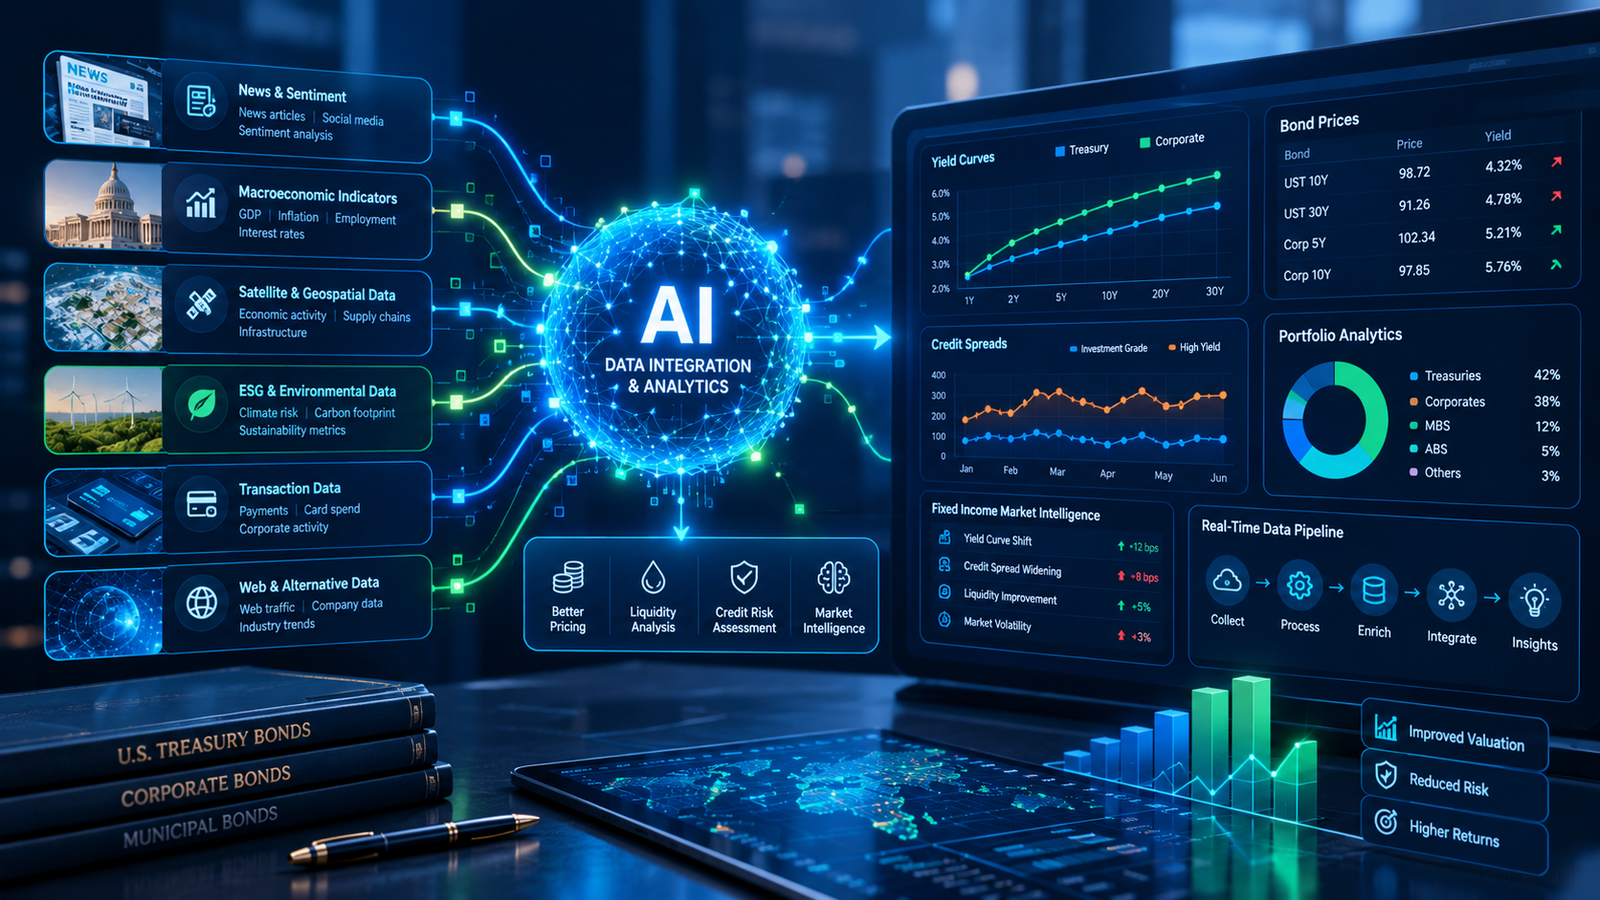
Primary topic: AI in Alternative Data Integration for Fixed Income Markets
Research focus: Alternative data, artificial intelligence, machine learning, corporate bonds, government bonds, credit spreads, bond liquidity, fixed income pricing, NLP, earnings calls, ESG data, macroeconomic data, satellite data, web data, transaction data, portfolio analytics, credit risk, bond trading, data integration, AI infrastructure, developers, startups, asset managers, banks and institutional investors
What Is Alternative Data in Fixed Income?
Alternative data refers to information that is not traditionally included in the core financial datasets used by bond investors and risk teams.
For fixed income, traditional data usually includes bond prices, yields, coupons, maturity dates, ratings, duration, spreads, issuer financial statements, benchmark curves and transaction information.
Alternative data expands this information universe.
Examples include:
- News and financial media
- Earnings-call transcripts
- Company websites and web traffic
- ESG reports and controversy data
- Satellite and geospatial information
- Supply-chain information
- Employment and hiring signals
- Consumer spending indicators
- App usage and download activity
- Credit and debit card activity where legally available
- Search trends
- Social and investor sentiment
- Patent and intellectual-property activity
- Climate and environmental datasets
- Shipping, logistics and commodity data
- Private-market and transaction datasets
The IMF’s 2025 technical note on AI in securities markets shows how widely alternative data is already used by investment funds. In the cited survey data, web scraping was reported by 43% of funds, credit and debit card data by 38%, social or sentiment data by 36%, app usage by 33%, web traffic by 31%, satellite data by 29% and geolocation by 24%.
This matters even more in fixed income because bond investors are often trying to answer questions that traditional price data answers poorly.
Is the issuer’s credit quality improving or deteriorating?
Is the spread compensating investors for the actual risk?
Is liquidity becoming weaker before the price fully adjusts?
Is an upcoming event likely to change refinancing or default risk?
Is the market underreacting to new information?
Alternative data can help answer these questions when it is properly integrated with conventional bond data.
Why Fixed Income Needs an AI Data Integration Layer
Fixed income is fundamentally different from a highly standardized equity market.
There may be thousands of bonds from the same issuer with different maturities, coupons, covenants, seniority levels, embedded options and liquidity characteristics.
A single issuer can therefore have multiple securities with different risk profiles.
At the same time, bond trading remains fragmented across dealers, electronic platforms and over-the-counter markets.
FINRA provides fixed-income datasets derived from TRACE and other sources, including transaction information, market breadth, sentiment, Treasury aggregates and other fixed-income statistics.
This creates an information problem.
The investor may have:
Prices, yields, spreads, trades and liquidity
Financials, filings and credit information
News, calls, reports and disclosures
Web, ESG, satellite, supply chain and other signals
The challenge is turning these disconnected sources into one investment signal.
AI becomes valuable at this integration point.
Alternative Data Categories for Fixed Income
| Data category | Examples | Fixed-income signal | AI opportunity |
|---|---|---|---|
| Text | News, filings, earnings calls | Credit deterioration or improvement | NLP and LLM extraction |
| Transaction | TRACE, dealer activity | Liquidity and price discovery | Pattern detection |
| ESG | Reports, controversies, ratings | Spread and refinancing risk | Text scoring and entity analysis |
| Web | Traffic, hiring, search behavior | Business momentum | Feature engineering |
| Macro | Inflation, rates, employment | Duration and credit-cycle risk | Forecasting and regime detection |
| Geospatial | Satellite and location data | Physical and operational risk | Computer vision and anomaly detection |
Research Study: Firm Embeddings Can Improve Credit Pricing
One of the most important recent studies for this topic comes from researchers at Princeton’s Bendheim Center for Finance.
The March 2025 paper, Upgrading Credit Pricing and Risk Assessment through Embeddings, examines whether high-dimensional information can improve the assessment of corporate credit risk beyond conventional credit ratings.
The researchers create what they call firm embeddings from the corporate bond holdings of mutual funds and insurance companies.
The idea is important for alternative-data architecture.
Instead of manually selecting a small number of variables, an embedding can represent a much larger information environment in a compressed mathematical form.
The researchers find that within broad credit-rating categories, these firm embeddings explain corporate credit spreads and credit-spread volatility better than credit ratings and distance-to-default measures.
This does not mean ratings become irrelevant.
It means that rating categories may not capture all the information that investors are already using.
For an AI platform, this suggests a powerful architecture:
+
Market Data
+
Investor Holdings
+
Issuer Information
+
Alternative Data
↓
AI Representation / Embedding
↓
Credit Spread + Risk Assessment
The important innovation is not simply using more data.
It is creating a representation that allows the model to capture relationships among information sources.
Research Study: Machine Learning Predicts Bond Risk Premiums
A 2025 study published in the Pacific-Basin Finance Journal examines machine learning for predicting bond risk premiums in China.
The researchers use macroeconomic, firm-level and bond-level predictors.
The study finds that machine learning, particularly neural networks, produces stronger out-of-sample performance than traditional linear benchmarks.
Several variables emerged as important predictors, including local per-capita fiscal expenditure, credit ratings and profitability- and intangible-related company characteristics.
The predictive gains were especially pronounced for:
- Lower-rated bonds
- Non-state-owned enterprises
- Periods of high economic-policy uncertainty
The study also reports that machine-learning forecasts can improve credit-rating accuracy.
This is highly relevant to alternative data integration because it demonstrates that AI does not have to replace conventional financial variables.
The strongest model can combine:
Macro + issuer fundamentals + bond characteristics + alternative information
That is a much more realistic architecture for an institutional fixed-income platform.
Research Study: Machine Learning Can Predict Individual Corporate Bond Returns
A February 2025 Journal of Banking & Finance study examines individual corporate bond return predictability using machine learning and a large set of predictors.
The researchers report an out-of-sample R-squared of 4.48% and an annualized Sharpe ratio of 3.27% in their research setting.
The models identified information from both aggregate market variables and individual bond characteristics.
Important predictors included:
- Bond-market returns
- Term and value-related factors
- GDP growth
- Downside risk
- Short-term reversal
- Return skewness
- Credit spreads
The study also finds that predictability changes with market conditions and becomes stronger during periods of high investor risk aversion, slower economic growth and stronger cross-sectional factor relationships.
This matters for alternative data because it suggests that a fixed-income AI model should not be treated as a static prediction engine.
The relationship between a signal and bond returns can change with the environment.
Source: Journal of Banking & Finance, Predicting Individual Corporate Bond Returns
Research Study: Machine Learning Text Analysis Can Improve Bond Information Extraction
Text is one of the most valuable alternative-data sources for fixed income because issuers continuously communicate information that may not immediately appear in structured datasets.
A 2024 study in the Journal of Empirical Finance examined machine-learning text analysis of Chinese bond-rating reports.
The researchers compared machine-learning text scoring with traditional bag-of-words sentiment approaches.
They found that machine learning could identify featured vocabulary that traditional methods miss, reduce sentiment misclassification and avoid treating every word as equally important.
The research also found that the machine-learning text score contributed useful information to bond pricing and performed better than conventional tone measures in addressing rating inflation in the studied market.
This is a major lesson for developers.
Simply counting positive and negative words is not enough.
Consider a statement such as:
“Liquidity remains adequate despite a material increase in refinancing requirements over the next twelve months.”
A basic sentiment model might classify this as relatively positive because of the word “adequate”.
A credit-focused model needs to understand that the important information may be the refinancing pressure.
The goal should therefore be financial meaning extraction, not generic sentiment analysis.
Research Study: LLMs Can Extract Credit Signals From Earnings Calls
Recent generative AI research makes alternative-data integration even more interesting.
A working paper by Moazzam Khoja examines whether a large language model can extract credit-relevant information from corporate earnings-call transcripts.
The research uses ChatGPT to assess default likelihood from earnings calls.
The model-generated score was able to forecast rating migration one year ahead beyond a traditional sentiment dictionary applied to the same text.
The study also found that the score could forecast short-term bond returns following earnings calls in situations where analysts disagreed about the firm.
This is particularly interesting because earnings calls contain more than sentiment.
They contain:
- Management explanations
- Forward-looking expectations
- Liquidity discussion
- Capital expenditure plans
- Debt-management commentary
- Customer and demand information
- Analyst questions
- Management responses under pressure
An LLM can potentially convert this unstructured information into structured features for a fixed-income model.
That is very different from using an LLM to simply summarize an earnings call.
Research Study: ESG Report Tone Can Affect Corporate Bond Spreads
ESG information is another important alternative-data category for fixed income.
A 2025 study in Energy Economics examined ESG report tone and corporate bond spreads using Chinese credit-bond data covering 2008 to 2022.
The researchers found that negative tone in ESG reports significantly widened corporate bond spreads.
The effect was stronger when report quality and market attention were higher.
The study also found that stronger ESG ratings and governance could reduce the adverse impact of negative report tone, while negative public sentiment could amplify the market reaction.
This creates an important distinction between:
ESG score
and
ESG information flow
An issuer can have a good historical ESG score while a new disclosure changes the market’s perception of risk.
AI can therefore monitor both the level and the change.
For fixed-income investors, this is valuable because the market may react to changing risk before a formal rating agency changes its assessment.
Source: Energy Economics, ESG Report Tone and Bond Spreads
Research Study: AI Adoption Can Improve Corporate Bond Liquidity
The relationship between AI and fixed income is not limited to investors.
A 2025 Journal of Financial Markets study examined AI adoption by bond dealers and its effect on U.S. corporate bond liquidity.
The researchers used LinkedIn profile information to estimate dealer-specific AI adoption and then constructed an AI-availability measure at the bond level.
Their results suggest that greater AI adoption by dealers improves liquidity across several measures, enhances dealers’ liquidity provision to customers and reduces frictions in dealer-customer OTC markets.
The study also reports that improved liquidity can strengthen the performance of multi-factor bond-pricing models and reduce certain pricing anomalies.
This finding expands the definition of alternative-data integration.
The AI system is not only analyzing alternative information.
AI itself can become part of the market infrastructure that changes:
- Price discovery
- Dealer selection
- Liquidity provision
- Pre-trade analysis
- Execution quality
Source: Journal of Financial Markets, AI Availability and U.S. Corporate Bond Markets
Research Evidence Dashboard
AI-focused research directions
Credit, returns, text, ESG, liquidity and market monitoring
Out-of-sample R² reported in a 2025 corporate-bond return study
Daily indicators used in a BIS AI market-monitoring system
Funds reporting web-scraping use in cited IMF alternative-data survey
What Alternative Data Should a Fixed-Income AI Platform Actually Integrate?
The answer depends on the investment or risk problem.
A credit analyst does not need exactly the same alternative data as an execution trader.
An insurance portfolio manager does not need exactly the same data as a hedge fund running relative-value strategies.
A bank treasury team has different objectives again.
| Business problem | High-value data | AI output |
|---|---|---|
| Credit deterioration | Filings, calls, news, ESG, fundamentals | Early-warning credit score |
| Bond valuation | Trades, spreads, fundamentals, peer bonds | Fair-value estimate |
| Liquidity | TRACE, dealer activity, order information | Liquidity probability and execution score |
| Macro risk | Rates, inflation, employment, policy data | Regime and scenario forecasts |
| Issuer business momentum | Web, hiring, supply chain, consumer data | Operating-momentum indicator |
| ESG and transition risk | ESG reports, controversies, environmental data | Dynamic ESG-credit signal |
AI-Powered Alternative Data Pipeline
TRACE + market feeds + filings + news + earnings calls + ESG + macro + approved alternative datasets
↓
Data Quality Layer
Deduplication + timestamp normalization + entity matching + missing-data checks
↓
AI Processing Layer
NLP + embeddings + anomaly detection + computer vision + forecasting
↓
Feature Store
Issuer features + bond features + market features + alternative-data signals
↓
Fixed Income Intelligence
Credit score + fair value + liquidity + spread forecast + risk alerts
↓
Portfolio / Trading Workflow
Research + screening + portfolio construction + execution + monitoring
AI for Bond Fair-Value Estimation
Fair-value estimation is one of the strongest use cases for alternative data.
A bond may trade infrequently.
This means the last observed transaction may not represent the current fair value.
AI can estimate fair value using:
- Recent trades in the same bond
- Comparable bonds from the issuer
- Sector spreads
- Rating
- Duration
- Liquidity
- Issuer fundamentals
- Market volatility
- Macro conditions
- Recent issuer disclosures
- News and event signals
MarketAxess is already moving in this direction. Its CP+ product uses AI-powered bond pricing and provides real-time pricing information for the investible bond universe, while its data solutions also support liquidity and pre-trade analysis.
FactSet announced in September 2025 that MarketAxess CP+ data would be integrated into its Workstation, bringing AI-powered fixed-income pricing information directly into an institutional investment terminal.
This is a significant competitor and market signal.
The opportunity is no longer theoretical.
Institutional platforms are already turning AI-powered fixed-income data into commercial products.
Industry Development: Bloomberg Is Using Human-in-the-Loop AI for Fixed Income Data
Bloomberg reported in May 2025 that it was using human-in-the-loop workflows to improve fixed-income data management, particularly for complex term sheets.
This is an important implementation lesson.
Bond documents contain complicated structures that automated systems can misunderstand.
Bloomberg’s approach combines AI-driven extraction with human subject-matter expertise to improve the quality of structured data.
For startups building fixed-income AI products, this suggests a better strategy than trying to make the entire pipeline autonomous from day one.
The architecture should be:
AI extraction → confidence score → human review → approved record → model training
Over time, high-confidence cases can become increasingly automated while difficult cases continue to receive expert review.
Industry Development: Tradeweb Is Moving AI Into Credit Research
Tradeweb disclosed in 2026 that it introduced TARA, an AI-powered research assistant for institutional credit trading.
The system is designed to help institutional U.S. credit-market participants transform trading data into real-time market intelligence and trading insights.
This is strategically important.
It shows that institutional fixed-income AI is moving beyond:
Data dashboard → AI research assistant → actionable market intelligence
A startup entering this market should therefore avoid building a simple dashboard with a chatbot attached.
The product needs to solve an actual investment workflow.
Industry Development: ICE Is Making Fixed-Income Data Available Through AI Platforms
In 2026, ICE announced availability of fixed-income datasets through leading AI platforms.
The datasets include:
- End-of-day fixed-income evaluations
- Enhanced evaluation transparency
- U.S. Treasury benchmark data
- FINRA TRACE data
- Municipal bond transaction data
ICE said its end-of-day evaluations cover more than 3 million financial instruments across more than 150 countries and more than 80 currencies.
This development points toward an important change in financial AI.
The future is not only about training private models.
It is also about making high-quality financial datasets usable inside AI workflows with proper licensing, provenance and controls.
Alternative Data Integration Is More Important Than Alternative Data Collection
Many startups make the same mistake.
They collect hundreds of datasets and assume more data automatically creates a better model.
It does not.
A dataset becomes valuable only when:
- It measures something economically relevant
- Its timestamp is understood
- Its revisions are tracked
- Its historical availability is known
- Its relationship to the target variable is tested
- It does not introduce unacceptable leakage
- It can be legally used
- It can be reproduced
- Its quality can be monitored
For example, a company website’s traffic might be useful for measuring business momentum.
But if historical traffic data was revised after the fact, using the revised value in a backtest can create look-ahead bias.
The AI may appear more accurate than it would have been in real time.
This is why data lineage is as important as model architecture.
Alternative Data Data-Lineage Architecture
Where did the data originate?
When was the information actually available?
How was raw information processed?
Which model generated the signal?
How did the signal influence the investment workflow?
AI and Fixed Income Liquidity
Liquidity is one of the most important areas where alternative data can add value.
A bond can have a reasonable theoretical valuation but still be difficult to trade.
AI can estimate liquidity using:
- Trading frequency
- Trade size
- Bid-ask behavior
- Dealer participation
- Recent transaction activity
- Volatility
- Issuer size
- Bond age
- Market stress
- Sector conditions
This becomes especially important during stressed markets.
The 2025 S&P Dow Jones Indices review showed how rapidly fixed-income markets can reprice during shocks. U.S. investment-grade spreads widened sharply during the April 2025 volatility episode before retracing later in the year, while high-yield spreads experienced an even larger move.
For AI developers, the implication is clear.
A liquidity model should not be evaluated only during calm markets.
It needs to be tested during:
- Rate shocks
- Credit spread widening
- Geopolitical events
- Liquidity stress
- Large issuance periods
- Dealer inventory changes
AI and the New Wave of AI-Related Corporate Debt
Alternative-data systems also need to understand structural themes affecting bond markets.
AI itself is now becoming a major fixed-income theme.
S&P Global reported that AI-related corporate issuance expanded significantly as technology companies and infrastructure businesses funded large capital expenditures.
MSCI also noted in September 2026 that AI-related bond issuance had become large enough to influence discussions about Treasury yields and broader debt-market supply.
Morningstar reported in July 2026 that bond issuance associated with AI-related infrastructure had accelerated and was testing investor demand, including significant high-yield issuance connected to data-center construction.
This creates a new alternative-data opportunity.
An AI fixed-income platform could monitor:
- Data-center construction spending
- Power demand
- AI-related debt issuance
- Issuer leverage
- Capital expenditure
- Free-cash-flow development
- Cloud demand
- Energy costs
- Technology-sector concentration
- Refinancing requirements
This is a good example of how alternative data can become thematic credit intelligence.
AI for Credit Spread Forecasting
Credit spreads represent compensation for credit and other risks beyond the benchmark risk-free rate.
AI can forecast spread movements using multiple information layers.
| Signal family | Examples | Possible output |
|---|---|---|
| Issuer | Leverage, cash flow, profitability | Issuer credit score |
| Bond | Maturity, coupon, seniority, liquidity | Bond-specific spread estimate |
| Macro | Rates, inflation, employment | Regime signal |
| Text | News, calls, filings | Event and credit signal |
| Alternative | Web, ESG, satellite, supply chain | Business momentum |
| Market | Flows, liquidity, volatility | Market-risk adjustment |
The model can then estimate:
Expected spread direction + confidence + key drivers
This is more useful for an analyst than a single unexplained number.
AI and Explainable Fixed Income Research
Explainability is especially important in fixed income because institutional investment decisions often require documentation.
A portfolio manager may need to explain why a bond was:
- Upgraded internally
- Downgraded internally
- Added to a watchlist
- Removed from a portfolio
- Assigned a higher spread requirement
- Flagged for liquidity risk
An AI system should therefore generate an evidence trail.
For example:
Issuer credit risk increased because recent earnings-call language indicates weaker demand, refinancing requirements increased, the issuer’s sector spread widened, recent bond liquidity deteriorated and negative ESG-related disclosures increased market attention
Confidence: Medium
Primary drivers: Refinancing risk, spread movement, earnings-call signal, liquidity deterioration
Human review: Required
This design makes AI useful without pretending that the model is infallible.
Competitor and Industry Benchmarking
The market already has several major players moving toward AI-powered fixed-income intelligence.
| Company / platform | Current direction | Lesson for startups |
|---|---|---|
| Bloomberg | AI-assisted fixed-income data extraction with human review | Data quality is a product feature |
| FactSet | AI-powered MarketAxess CP+ pricing integrated into workstation | AI becomes more valuable inside existing workflows |
| MarketAxess | AI pricing, liquidity and dealer analytics | Execution and pricing are converging with AI |
| Tradeweb | AI research assistant for institutional credit trading | Research copilots need real market data |
| ICE | Fixed-income data availability through AI platforms | Data licensing and AI accessibility are becoming connected |
| S&P Global | Cross-asset data and AI-powered fixed-income intelligence | Cross-asset signals can strengthen bond analysis |
The competitive lesson is clear.
A new company does not need to beat Bloomberg, ICE or S&P Global at raw data coverage.
It can win by solving a narrower workflow better.
Where Startups Can Still Compete
A startup could focus on a specific underserved problem.
Strong opportunities include:
- AI Credit Early-Warning Platform for asset managers
- Bond Fair-Value API for fintech applications
- Alternative Data Feature Store for fixed-income quant teams
- AI Earnings-Call Credit Analyzer
- Bond Liquidity Forecasting API
- ESG-to-Credit Intelligence Engine
- Private Credit Alternative Data Platform
- Fixed-Income Research Copilot
- Issuer Monitoring Platform
- AI Corporate Bond Watchlist Engine
A particularly attractive product could combine alternative data with an issuer-monitoring workflow.
Instead of asking an analyst to manually monitor 500 issuers, the system could continuously scan approved data sources and notify the analyst only when the risk profile changes materially.
Developer Guide: How to Build the System
Developers should avoid starting with the model.
Start with the data contract.
Data layer
Build connectors for:
- Market feeds
- TRACE and other approved transaction datasets
- Issuer filings
- News
- Earnings calls
- ESG data
- Macroeconomic datasets
- Licensed alternative data
Entity layer
Create a consistent mapping between:
Company → Issuer → Parent → Bond → CUSIP / identifier → Sector → Country → Industry
Entity resolution is critical because alternative data may identify a company differently from bond-market systems.
Feature layer
Build reusable features rather than directly sending raw datasets to an LLM.
Examples include:
- News intensity score
- Refinancing pressure score
- Liquidity deterioration score
- ESG controversy acceleration
- Management uncertainty score
- Web activity change
- Hiring momentum
- Spread momentum
- Issuer financial stress
Model layer
Use different models for different tasks.
- Gradient boosting for structured credit features
- Transformers and LLMs for document intelligence
- Embeddings for entity and semantic similarity
- Time-series models for spread and liquidity forecasting
- Anomaly detection for unusual issuer behavior
- Computer vision for geospatial or satellite information
Decision layer
The final output should be understandable.
For example:
Issuer X: Credit Watchlist Risk Increased
- Refinancing pressure increased
- Bond spread widened relative to sector peers
- Negative management-language signal increased
- Liquidity weakened over the last 20 trading sessions
- ESG-related market attention increased
Startup MVP Roadmap
Month 1: Narrow the problem
Choose one use case such as corporate-bond credit monitoring
Month 2: Build the data foundation
Connect bond, issuer, market and one or two alternative-data sources
Month 3: Build the first AI signal
Create one explainable credit or liquidity score
Month 4: Add document intelligence
Process filings, earnings calls and relevant news
Month 5: Backtest and validate
Use point-in-time datasets and realistic transaction assumptions
Month 6: Pilot with analysts
Measure alert quality, analyst time saved and investment usefulness
How Businesses Should Measure ROI
The wrong KPI is:
“How accurate is the AI?”
A fixed-income AI system should be evaluated against the business workflow.
| KPI | Business question |
|---|---|
| Analyst time saved | Can analysts cover more issuers? |
| Signal precision | Are alerts actually useful? |
| Early-warning lead time | How early can deterioration be detected? |
| Coverage | How many issuers can be monitored continuously? |
| False-positive rate | How much analyst workload does the AI create? |
| Investment impact | Does the signal improve portfolio decisions after costs? |
| Data quality | Can every important signal be traced to its source? |
Connection With Other AICOPSE Research
Alternative data integration becomes much more powerful when connected with other AI-finance capabilities.
For example, AI-generated fixed-income signals can feed into AI in Dynamic Risk Management and Stress Testing, where alternative signals can become inputs to scenario analysis and risk monitoring.
Credit-related alternative data can also complement AI in Credit Scoring and Underwriting, particularly when assessing corporate borrowers and credit exposures.
Portfolio teams can combine alternative-data signals with AI in Quantitative Portfolio Optimization and Asset Allocation to improve security selection, portfolio weighting and risk management.
Trading teams can connect these signals with AI in Algorithmic Trading and Automated Strategy Execution when moving from research signals toward execution.
For broader market strategy development, see AI in Stock Market Trading Strategy Development.
This creates a broader AI investment architecture:
↓
AI Signal Generation
↓
Credit + Liquidity + Market Risk
↓
Portfolio Optimization
↓
Execution
↓
Continuous Monitoring
Key Risks of Alternative Data Integration
Data Leakage
A model may accidentally use information that was not available at the time of the investment decision.
This can make backtests look far better than live performance.
Survivorship Bias
If the dataset contains only companies or bonds that still exist, the model may underestimate historical failures and defaults.
Data Revisions
Economic datasets can be revised after publication.
A production-grade backtest should preserve what was actually known at each point in time.
Vendor Concentration
Depending heavily on one alternative-data provider can create pricing, availability and continuity risks.
False Economic Relationships
A model may discover correlations that have no durable economic explanation.
This is particularly dangerous when thousands of alternative features are tested.
Model Drift
A data source that was useful five years ago may lose predictive power.
AI systems therefore need continuous feature monitoring.
Legal and Licensing Risk
Alternative data must be sourced and used under appropriate licenses and privacy requirements.
The cheapest dataset is not necessarily the safest dataset for institutional deployment.
Expert Recommendation
The strongest strategy for financial institutions and startups is to treat alternative data as an intelligence layer, not as a replacement for fundamental credit analysis.
A high-quality implementation should follow five principles.
- Start with an economic question rather than starting with an AI model
- Use point-in-time data so research reflects information actually available at the time
- Combine alternative signals with traditional fixed-income variables
- Explain why a signal changed rather than presenting only a score
- Measure live business impact rather than optimizing only statistical accuracy
Bloomberg’s human-in-the-loop approach is particularly relevant for complex fixed-income data because it shows that institutional AI can benefit from combining automated extraction with domain expertise.
The BIS provides another useful model for the future. Its 2025 research combined a recurrent neural network using more than 100 daily indicators with an LLM that searched recent news based on the indicators driving the model’s signal. The system identified market dysfunction up to 60 business days ahead in its testing and was designed to explain why the model was becoming more concerned.
The lesson is powerful:
Prediction becomes more useful when AI can also explain what changed and why it matters.
Expert Quote
That principle fits fixed-income alternative data extremely well.
A portfolio manager does not only need to know that a bond’s risk score increased.
The manager needs to understand whether the change came from:
- New refinancing pressure
- Worsening liquidity
- Sector stress
- Management commentary
- Macroeconomic deterioration
- Negative ESG information
- Investor flows
- Market-wide repricing
AI Maturity Model for Alternative Data in Fixed Income
| Stage | Capability | Typical output |
|---|---|---|
| Foundation | Traditional bond and market data | Basic analytics |
| Integrated | Traditional + alternative data | Expanded research coverage |
| Predictive | ML forecasting and anomaly detection | Risk and spread signals |
| Multimodal | Text + market + issuer + alternative data | Integrated issuer intelligence |
| Adaptive | Continuous learning and regime detection | Dynamic risk and valuation |
| Decision intelligence | AI integrated into portfolio and execution workflows | Actionable investment intelligence |
Future Predictions: 2027–2030
2027: Fixed-Income AI Moves From Data Discovery to Data Fusion
The next stage will not be about discovering another alternative dataset.
The competitive advantage will come from combining many imperfect datasets.
Platforms will increasingly create issuer-level intelligence from:
Market + financial + text + ESG + macro + behavioral + operational data
The best platforms will also maintain data lineage so users can see exactly where each signal came from.
2028: Bond Research Becomes More Event-Driven
AI will increasingly monitor issuer events continuously rather than waiting for quarterly analyst reviews.
An AI system could detect:
- Unexpected management language
- Refinancing changes
- Sudden liquidity deterioration
- Unusual spread movements
- Negative news clusters
- Changes in business activity
The result will be a continuous issuer-monitoring system.
2029: Multimodal Credit Models Become More Common
Fixed-income models will increasingly combine:
Financial and market data
Filings, calls and news
Satellite and geospatial signals
Supply chain and issuer relationships
This could create richer credit-risk representations than models relying exclusively on structured financial variables.
2030: AI Becomes the Research Operating Layer
By 2030, leading fixed-income teams may use AI as the layer connecting:
Data → Research → Risk → Portfolio Construction → Execution → Monitoring
The AI will not necessarily make every investment decision.
Instead, it will continuously organize the information required to make those decisions.
High-Value Opportunities by User Type
| User | Best AI opportunity | First product to build |
|---|---|---|
| Asset manager | Issuer monitoring | AI credit watchlist |
| Bank | Credit and liquidity intelligence | Early-warning platform |
| Hedge fund | Alternative-data alpha | Signal research engine |
| Insurance company | Credit and capital-risk intelligence | Portfolio risk monitor |
| Fintech | Bond pricing APIs | Fixed-income intelligence API |
| Startup | Narrow workflow automation | AI research copilot |
| Developer | Data and model infrastructure | Alternative-data feature platform |
Frequently Asked Questions
What is alternative data in fixed income?
Alternative data in fixed income refers to information outside traditional bond prices, yields, ratings and financial statements. Examples include news, earnings calls, ESG reports, web activity, satellite information, supply-chain signals, consumer data, sentiment and other approved datasets.
How does AI use alternative data for bond investing?
AI can transform alternative data into structured features, identify nonlinear relationships, detect changes in issuer behavior, forecast credit or liquidity conditions and combine alternative signals with traditional bond-market variables.
What alternative data is most useful for corporate bonds?
There is no universal best dataset. High-value categories can include earnings-call text, news, financial filings, ESG information, transaction data, macroeconomic indicators, web activity, supply-chain information and other issuer-specific operating signals.
Can AI replace credit ratings?
AI can potentially provide additional or more timely credit information, but it should not automatically be treated as a replacement for regulated credit ratings. Recent research on firm embeddings suggests that high-dimensional information can explain credit spreads beyond conventional ratings, which supports using AI as an additional credit-intelligence layer.
Why is alternative data difficult to use in fixed income?
Fixed-income instruments have different maturities, structures and liquidity characteristics. Alternative data also creates challenges around timestamps, entity matching, licensing, revisions, data leakage, model drift and economic relevance.
Can LLMs analyze corporate bond risk?
LLMs can extract information from earnings calls, filings, news and other unstructured documents. Recent research suggests that LLM-based analysis of earnings-call transcripts can provide credit-relevant information, but the output should be validated and combined with structured financial and market data.
How can startups compete with Bloomberg and other large financial-data companies?
Startups do not need to replicate the data coverage of major vendors. They can focus on narrow workflows such as issuer monitoring, credit early warnings, bond fair-value estimation, ESG-credit intelligence, liquidity forecasting or fixed-income research copilots.
What is the biggest mistake when building alternative-data AI?
The biggest mistake is assuming that more datasets automatically create a better model. Data quality, economic relevance, point-in-time availability, licensing, entity resolution and leakage controls are often more important than simply increasing the number of features.
Final Perspective
AI is transforming alternative data in fixed income from a collection problem into an integration problem.
The market already has enormous quantities of information:
-
Bond trades via systems like TRACE
-
Financial statements and earnings reports from issuers
-
Research from analysts
-
ESG disclosures from companies
-
Economic indicators from macroeconomic agencies
-
Operational signals from websites
-
Flows and positioning data from investors
The challenge is that these sources exist in different formats, at varying frequencies, and with disparate levels of reliability. AI bridges this gap.
Recent research provides several compelling reasons to embrace this shift:
-
Princeton firm-embedding research shows that high-dimensional data explains corporate credit spreads and spread volatility better than broad rating categories.
-
Chinese bond market studies demonstrate that neural-network models improve bond risk-premium forecasting, particularly for lower-rated and non-state-owned issuers.
-
Individual corporate bond research proves meaningful out-of-sample return predictability using machine learning across numerous predictors.
-
Text-analysis findings reveal that machine learning extracts financially relevant vocabulary from bond-rating reports beyond traditional sentiment scoring.
-
LLM research indicates that earnings-call transcripts harbor valuable credit information that can be converted into predictive signals.
-
ESG studies confirm that the tone of corporate ESG disclosures directly influences bond spreads.
-
Research on AI adoption by bond dealers highlights how AI reshapes market structure by enhancing liquidity provision and reducing OTC trading frictions.
The industry is moving in the same direction:
-
Bloomberg applies human-in-the-loop AI to complex fixed-income data.
-
FactSet integrates MarketAxess AI-powered pricing data into its institutional workstation.
-
Tradeweb offers AI-powered research capabilities for institutional credit trading.
-
ICE makes fixed-income datasets accessible within AI environments.
-
MarketAxess leverages AI for bond pricing, liquidity, and dealer analytics.
These developments confirm that alternative-data AI is becoming a core component of the fixed-income technology stack.
Consequently, the next competitive advantage will not simply come from having more data—it will come from how effectively you connect it.
It will be having a better data-to-decision pipeline.
↓
Clean Data
↓
Entity Resolution
↓
AI Feature Extraction
↓
Credit + Liquidity + Valuation Signals
↓
Explainable Research
↓
Portfolio and Risk Decision
↓
Continuous Monitoring
For developers, the opportunity is to build reliable infrastructure.
For startups, the opportunity is to solve one expensive fixed-income workflow better than existing systems.
For asset managers, the opportunity is to expand research coverage without expanding analyst workload at the same rate.
For banks, the opportunity is to improve credit, liquidity and market intelligence.
For fintech companies, the opportunity is to expose fixed-income intelligence through APIs and embedded research products.
The most valuable systems will not say:
“AI predicts this bond will outperform.”
They will say:
“This issuer’s risk profile has changed, these five information sources explain the change, the strongest signals are refinancing pressure and liquidity deterioration, comparable bonds are pricing a different risk level, and the model’s confidence is medium.”
That is the difference between an AI prediction engine and an AI-powered fixed-income research platform.
Research Sources
- Princeton Bendheim Center for Finance — Upgrading Credit Pricing and Risk Assessment through Embeddings
- Pacific-Basin Finance Journal — Predicting Bond Risk Premiums with Machine Learning: Evidence from China
- Journal of Banking & Finance — Predicting Individual Corporate Bond Returns
- Journal of Empirical Finance — Tone or Term: Machine-Learning Text Analysis, Featured Vocabulary Extraction, and Evidence from Bond Pricing in China
- SSRN — Large Language Models, Information Processing, and Post-Earnings Announcement Drift in Corporate Bonds
- Energy Economics — ESG Report Tone and Bond Spreads
- Journal of Financial Markets — AI Availability and U.S. Corporate Bond Markets
- BIS Working Paper 1291 — Harnessing Artificial Intelligence for Monitoring Financial Markets
- IMF — Regulatory Considerations Regarding Accelerated Use of AI in Securities Markets
- FINRA Developer Center — Fixed Income API and TRACE Data
- FINRA — Fixed Income Data
- Bloomberg — Transforming Fixed Income Data Management With AI and Human Expertise
- FactSet — AI-Powered Fixed Income Data and MarketAxess CP+
- S&P Global and MarketAxess — Fixed Income Market Transparency and AI-Powered CP+
- S&P Dow Jones Indices — 2025 Fixed Income Index Products Report
- MSCI — The Limits of AI Debt as a Driver of Treasury Yields
- Morningstar — Bond Issuance Backing AI Investment Tops $250 Billion
- MarketAxess — 2026 Annual Report and AI-Powered Fixed Income Data Solutions
- Tradeweb — 2026 Update and TARA AI-Powered Credit Trading Research Assistant
- ICE Fixed Income Data Available Through Leading AI Platforms

Leave a Reply